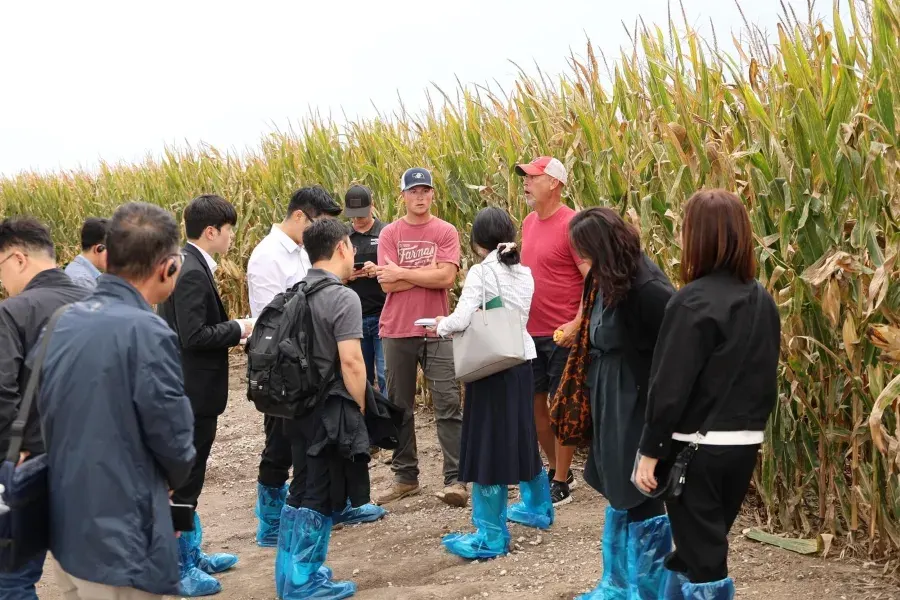
The U.S. Grains & BioProducts Council escorted a 19-member South Korean feed and food corn buyer delegation on a multi-state tour of the U.S. corn export chain in September 2026, covering farms, ethanol facilities, grain handling sites and Pacific Northwest export terminals, as U.S. corn holds more than 80% of South Korea's import market so far this year.
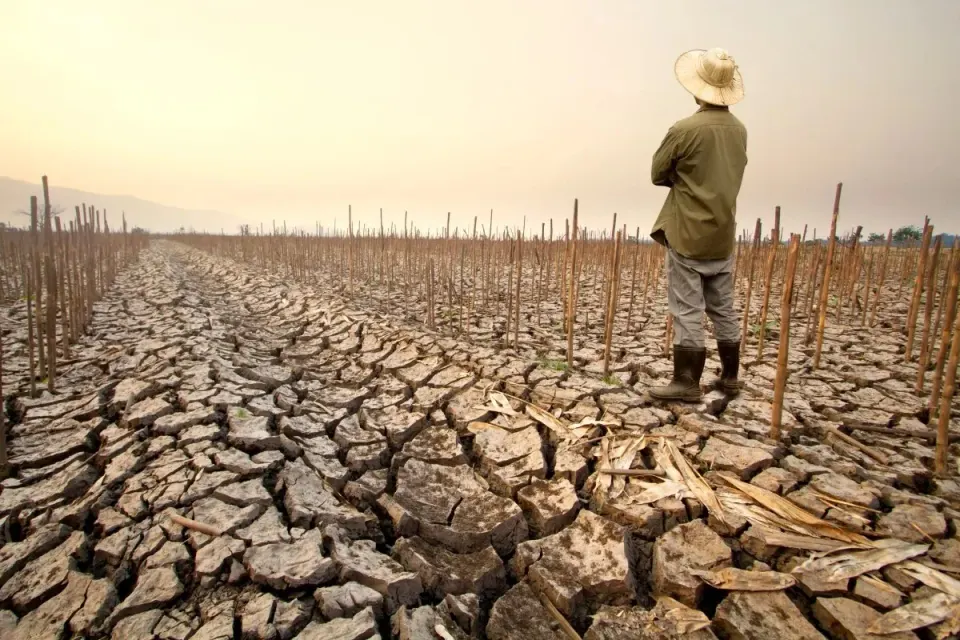
A strengthening El Niño event, combined with fertilizer shortages, geopolitical tensions, and elevated energy costs, could push global food and feed commodity prices up by 14–16%, according to procurement consultancy Beroe. Key feed ingredients including corn, vegetable oils, and sugar face varying levels of supply and price risk, with the full market impact potentially not materialising until 2028.
Corn, soybean, and wheat futures all closed lower on 23 September 2026, pressured by weak ethanol output, lower EU and UK crop forecasts from Coceral, ongoing Black Sea military strikes, and shifting South American production outlooks, according to an ADM Investor Services market commentary.
Grain and oilseed futures closed mostly lower on 22 September 2026, according to ADM Investor Services analyst Mark Soderberg. Corn drifted back toward session lows while managed money extended a long position that ADMIS described as a potential record high. Soybeans finished mixed, soybean meal protein value reached a seven-month high, and wheat futures fell sharply amid ongoing Black Sea conflict and softening global supply signals.
Corn futures pulled back toward technical support on September 23, 2026, erasing Monday's gains, while a USDA daily export sale to Mexico, a high-stakes Xi-Trump summit in Washington, a proposed U.S. diesel export ban, and a projected 70% surge in global biofuel output by 2030 combined to create a complex backdrop for feed-grain and oilseed markets.
Philippine corn production is projected to fall 14.4% to 2.08 million tonnes following typhoon damage, with El Niño conditions forecast to intensify into late 2026. The supply squeeze is accelerating feed-industry interest in drought-tolerant millet as a partial corn substitute, while European and Black Sea export prices remain broadly stable.
A series of typhoons in the Philippines has reduced July–September 2026 corn production by an estimated 14.4%, tightening regional feed grain availability and pushing up input cost risk for Southeast Asian feed manufacturers. CBOT December 2026 corn futures are trading around 529 USc/bu, while buyers consider alternative grains including millet.
Italy's soft wheat flour exports rose nearly 15% year on year in the first half of 2026, with the United States becoming the largest buyer after a 38% surge in imports, even as Black Sea wheat prices remain subdued and global grain benchmarks stay under pressure.
Tunisia's state grains agency has purchased around 125,000 tonnes of soft wheat at $311.72–314.23/tonne C&F for October–December shipment, setting a clear pricing floor for Mediterranean destinations and limiting near-term downside for Black Sea and EU export origins.
Ukraine's Cabinet of Ministers Resolution No. 675 introduces mandatory producer-register verification for rapeseed exporters from 1 July 2026 and soybean exporters from 1 September 2026, replacing chamber-of-commerce certificates as the basis for export-duty exemptions. The change raises working-capital and administrative costs for traders and is already contributing to a modest convergence of Ukrainian rapeseed prices toward EU benchmarks.
Chicago corn futures rose on 21 September 2026, driven by trader positioning ahead of US–China talks that could unlock new Chinese grain purchases and by persistent Black Sea supply uncertainties. Gains were broad-based but moderate, with the market still awaiting concrete outcomes from the summit.
Argentina's 2026/27 wheat output is forecast to fall sharply from the previous season's record, while war-related disruptions continue to constrain Black Sea exports. Together, the two developments are tightening global high-quality wheat availability and pushing Chicago futures to a multi-year high, raising import costs for buyers in North Africa, the Middle East and Asia.