Argentina Wheat Crop Decline and Black Sea Disruptions Tighten Global Milling Wheat Supply
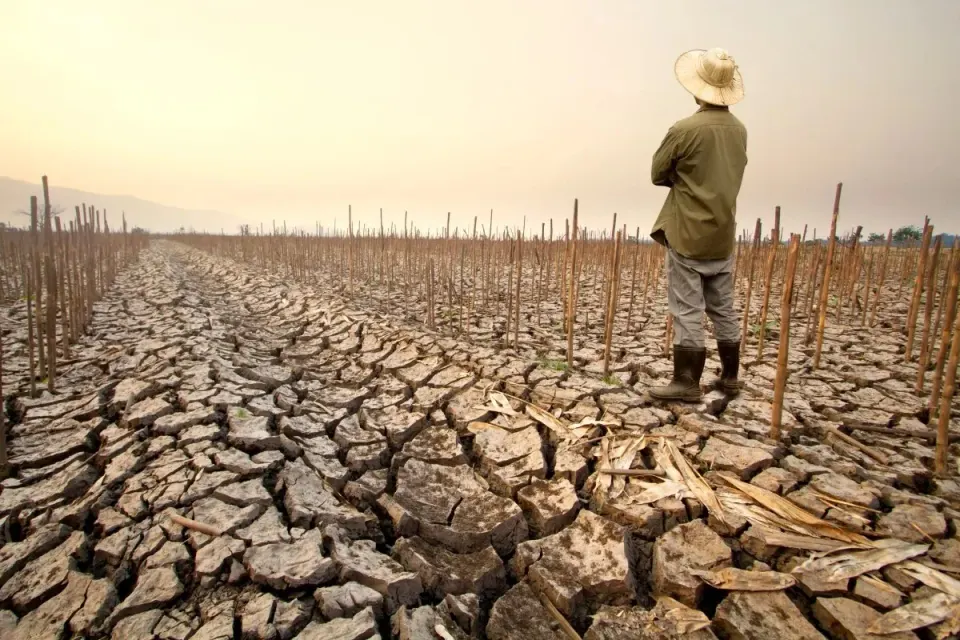
Argentina's 2026/27 wheat output is forecast to fall sharply from the previous season's record, while war-related disruptions continue to constrain Black Sea exports. Together, the two developments are tightening global high-quality wheat availability and pushing Chicago futures to a multi-year high, raising import costs for buyers in North Africa, the Middle East and Asia.
Argentina's wheat production is forecast to drop significantly in 2026/27, removing a key Southern Hemisphere supply cushion at the same time as Black Sea shipments remain under pressure from the ongoing Russia–Ukraine war, according to CMB News (September 23, 2026).
The Buenos Aires Grains Exchange projects Argentine wheat output falling from 27.8 million tonnes in the previous season to 23.4 million tonnes in 2026/27, a decline of roughly 4.4 million tonnes. The drop stands in contrast to Argentina's broader grains complex, which the exchange expects to reach a record 157.9 million tonnes in 2026/27, driven by soybeans at 53.6 million tonnes and corn at 66 million tonnes. Wheat is described by CMB News as "clearly the weak link" within that record total.
The reduced Argentine exportable surplus is compounding a separate tightening on the Black Sea. Russian wheat exports in September are projected at approximately 1 million tonnes, compared with around 5 million tonnes in the same month a year earlier, according to the CMB News report. Ukrainian shipments are seen at around 1 million tonnes for September, roughly half the level recorded in September of the previous year, as infrastructure attacks slow logistics.
The twin supply constraints have contributed to a sharp rally in Chicago wheat futures, which have risen approximately 40% from June lows to a three-and-a-half-year high, CMB News reported. Physical prices, however, showed more limited movement: Ukrainian feed-grade wheat (14% moisture maximum) at Odesa was quoted at 0.144 EUR on a CPT basis as of September 21, while Ukrainian Grade 3 wheat at Odesa was quoted at 0.157 EUR CPT. German feed-grade wheat at Drentwede was quoted at 0.242 EUR EXW on the same date, with all three showing no change from the prior quote.
Ukrainian FOB offers for 11.50% protein wheat out of Odesa have eased in recent weeks, with values quoted at 0.126–0.138 EUR FOB, reflecting freight and risk discounts according to CMB News, though the publication notes the overall global price trend is higher.
Agronomic risks add further uncertainty to the Argentine projection. CMB News cited regional reports indicating that approximately 10% of Argentina's wheat area — about 160,000 hectares — is now rated in "regular" condition due to below-normal September rainfall. Short-term weather models were said to point to rising temperatures followed by a passing front with scattered, moderate rains that "may be patchy rather than widespread." The publication noted that if those showers underperform, yield prospects could fall below the Buenos Aires Grains Exchange's current forecast.
The combination of factors is narrowing the pool of competitively priced milling wheat available to importers in North Africa, the Middle East and Asia who had delayed purchases, according to CMB News. The report characterised the market as entering "a phase of tighter high-quality supplies and stronger basis levels rather than outright shortage," and suggested Argentina's role could shift from a price-capping supplier to a regional balancer, contingent on weather outcomes.
For feed industry participants, CMB News highlighted that larger South American corn supplies in 2026/27 could cap feed wheat usage where quality is high and open substitution opportunities later in the season.
Prepared with AI assistance and reviewed by the editorial team.