The European Feed Manufacturers Federation (FEFAC) has projected a soybean meal supply gap of at least 5 million tonnes in the EU for the 2026-27 marketing year, driven by drought, Black Sea trade disruptions, and sourcing constraints tied to the EU Deforestation Regulation. The federation estimates the combined cost impact on the EU feed and livestock sector could reach approximately EUR 1.4 billion and has called on EU institutions to act urgently to protect feed security.
Strong soybean meal exports from Argentina — close to 3 million tonnes in August 2026 — driven by sustained buying from the EU, Vietnam, Türkiye and Indonesia, are keeping Argentine crushing margins attractive and supporting global soybean demand. FOB soybean prices in Ukraine, the US and China remained broadly flat in euro terms in mid-September, while emerging weather risks in Brazil's Mato Grosso introduce potential upside price risk later in the 2026/27 season.
Grain futures moved higher overnight on September 16, 2026, led by a surging soybean meal market that reached a 2.5-year high. Corn, soybeans, and wheat also posted gains, while market participants awaited the Federal Reserve's anticipated interest rate decision. Ongoing heavy rainfall in the Corn Belt, elevated crude oil prices tied to Middle East supply disruptions, and developing U.S.-China trade talks added further context to commodity market moves.
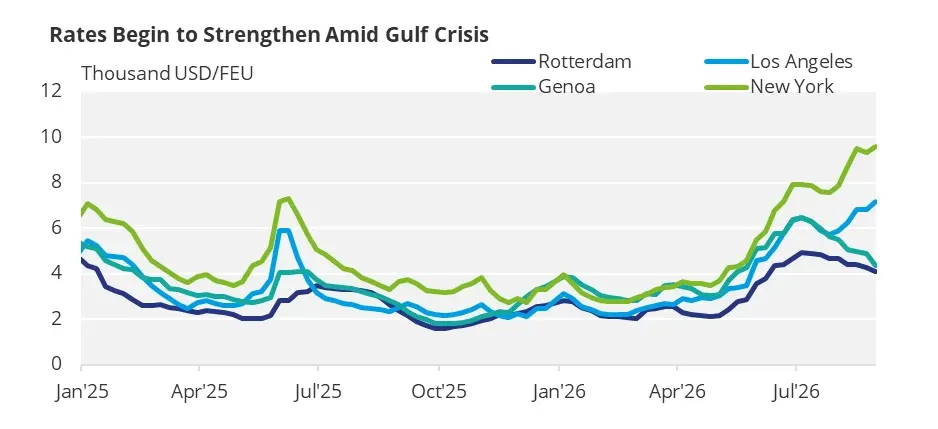
A rapidly intensifying El Niño is tightening water levels at the Panama Canal and prompting precautionary draft restrictions, according to an analysis by agribusiness consultant Alê Delara published by CZ App on 17 September 2026. The weather event could raise US Gulf-to-Asia shipping costs, eroding US soybean and corn competitiveness and redirecting Asian demand toward Brazil — but the same climate risks that could lift Brazilian export premiums also threaten its domestic harvest and push up farm input costs.
Soybean futures closed lower on 17 September 2026 following a volatile trading session, while soymeal prices moved sharply higher, according to a Reuters report cited by MarketScreener. Specific price levels and market drivers were not available from the accessible portion of the source.
US poultry by-product meal prices climbed close to all-time highs in early September 2026, rising 18.7% in a month as constrained global fishmeal availability pushed aquafeed formulators toward alternative proteins. Both IFFO and the FAO flagged continued tightness in fishmeal markets, driven by lower fishing quotas in South America and sustained aquaculture demand in China.
U.S. corn and soybean futures rebounded on Monday, 14 September 2026, driven by technical buying and strong export inspection data, while wheat futures moved lower amid persistent demand pressure. December corn settled at $5.3325 per bushel and November soybeans reached $13.0425, with weekly soybean export inspections surging nearly 45% above the prior week and exceeding analyst forecasts. Wheat remained under pressure as cumulative 2026/27 inspections tracked roughly 28% below last year's pace.
The USDA's September WASDE trimmed 2026/27 US corn ending stocks and slashed production forecasts, while soybean ending stocks edged lower on stronger export demand. Wheat balances were broadly stable. Meanwhile, Saudi Arabia's shutdown of its East-West pipeline and record-high diesel cracks are adding freight and energy cost pressure that feed manufacturers and ingredient traders will need to monitor closely.