Corn and Soybean Futures Rally on Export Demand as Wheat Slips in U.S. Grain Markets
U.S. corn and soybean futures rebounded on Monday, 14 September 2026, driven by technical buying and strong export inspection data, while wheat futures moved lower amid persistent demand pressure. December corn settled at $5.3325 per bushel and November soybeans reached $13.0425, with weekly soybean export inspections surging nearly 45% above the prior week and exceeding analyst forecasts. Wheat remained under pressure as cumulative 2026/27 inspections tracked roughly 28% below last year's pace.
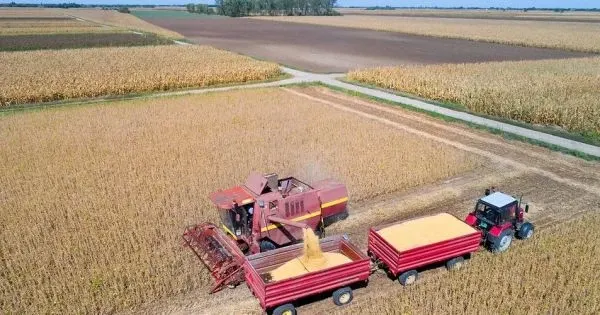
U.S. corn and soybean futures returned to positive territory on Monday, 14 September 2026, as technical buying and favourable export inspection figures lifted both commodities, while winter wheat futures declined amid ongoing export weakness.
Corn Futures Recover Despite Lower USDA Yield Estimate
December corn futures settled 3 cents higher at $5.3325 per bushel, recovering from overnight weakness as buyers returned during the session. March corn also advanced, gaining 2.5 cents to $5.48 per bushel. The rebound came as the market absorbed USDA's latest supply outlook, which reduced the 2026 national corn yield estimate to 178.5 bushels per acre, while projected production remained at 15.8 billion bushels. Ending stocks were revised down by 86 million bushels to 1.567 billion bushels.
Weekly corn export inspections for the period ending 10 September totalled 60.1 million bushels, down roughly 9% from the prior week but within the range of analyst expectations of 49.2 million to 69.9 million bushels. Mexico, South Korea, Japan, Colombia and Indonesia were the five leading destinations. Cumulative inspections for the 2026/27 marketing year reached 85.6 million bushels, running fractionally behind the prior year's pace. USDA maintained its corn export forecast at 3.3 billion bushels.
Soybeans Post Stronger Gains on Export Surge
Soybeans delivered the stronger percentage recovery of the two major row crops. November soybean futures rose 7.75 cents to $13.0425 per bushel, while January soybeans gained 8.25 cents to $13.2025. Strength extended across the complex, with October soybean meal gaining roughly 1% and October soybean oil advancing almost 0.75%.
The export data for soybeans was particularly notable. Weekly soybean inspections reached 24.7 million bushels, nearly 45% above the previous week, and surpassed the full range of analyst expectations of 11 million to 22 million bushels. China, Japan, Indonesia, Egypt and Bangladesh were the five leading destinations. However, cumulative soybean inspections since 1 September totalled 33.6 million bushels, running 16% below last year's pace — a contrast between strong weekly shipments and a weaker cumulative performance that analysts said would remain an important factor for commodity prices.
On the processing side, analysts expected August crush volume of 211.55 million bushels, compared with 216.64 million in July, with soybean oil stocks projected at 1.257 billion pounds as of 31 August. If realised, the crush would represent the strongest August on record despite declining from July, adding domestic processing demand as another variable for producers evaluating marketing and storage decisions.
Wheat Declines as Cumulative Exports Lag
Wheat diverged from the broader grain rally. December Chicago SRW futures fell 3.25 cents to $7.22 per bushel, while December Kansas City HRW dropped 6 cents to $7.9250, with technical selling weighing on prices during the morning session. Weekly wheat export inspections offered some support, increasing 6% to 16.8 million bushels and coming in near the upper end of analyst expectations. Japan, Mexico, the Philippines, Thailand and Vietnam were the leading destinations. Nevertheless, cumulative 2026/27 wheat export inspections stood at 208.5 million bushels, roughly 28% below the previous year's pace, maintaining pressure on the demand outlook.
Weather and Macro Conditions Add Uncertainty
Weather forecasts indicated that Iowa and northern Illinois could receive another 2 to 3 inches of rain between Tuesday and Friday, while portions of the eastern Corn Belt and Great Lakes could see roughly an additional inch. Macroeconomic signals were mixed: crude oil strengthened, the U.S. dollar firmed and Treasury yields moved higher — conditions that can influence export competitiveness and input costs across the agricultural sector.
With harvest advancing, market attention is increasingly focused on realised yields, basis behaviour, storage capacity and export demand as traders assess whether Monday's corn and soybean rally represents the beginning of a broader trend or a short-term technical rebound heading into the 2026/27 marketing year.
Prepared with AI assistance and reviewed by the editorial team.