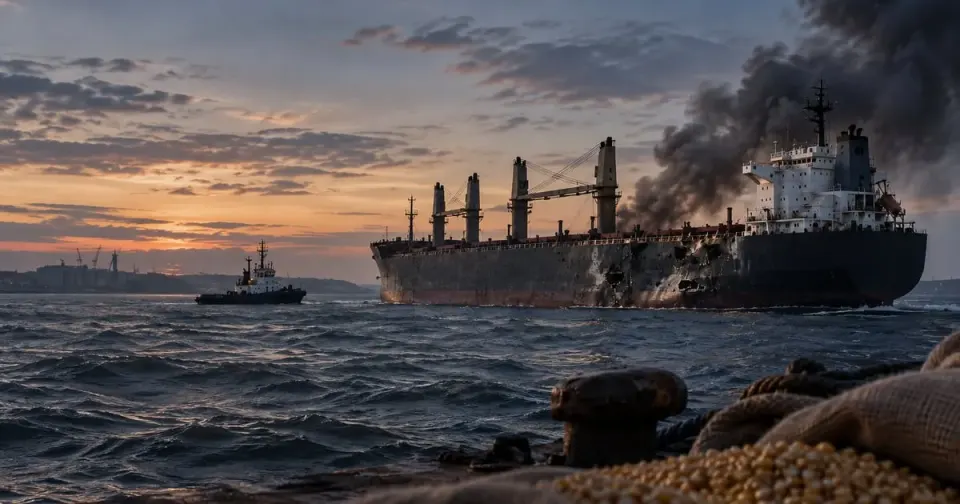
Drone attacks on merchant ships in the Black Sea this week, including strikes that sank at least one vessel off Bulgaria and Romania, have disrupted key grain export corridors and pushed Euronext front-month corn above €300/t for the first time, with wheat futures also firming. The incidents compound an already tight European grain balance marked by sharply reduced French corn output and historically low projected ending stocks for 2026/27.
UK FOB London pea prices have slipped modestly week-on-week as the 2026 domestic harvest under-delivered at roughly 69% of target, while stable and low Ukrainian FCA Odesa offers continue to cap upside for feed users.
Russia's Agriculture Ministry has formally proposed a 12-month moratorium on bankruptcy proceedings for grain producers after export bottlenecks caused a domestic price collapse, while EU and Black Sea physical wheat prices remained broadly flat. The Ministry of Economic Development has raised concerns about systemic financial risks, requesting evidence of exceptional circumstances before endorsing the measure.
USDA's latest quarterly grain stocks report shows US corn inventories rose 35% year-on-year to 2.10 billion bushels as of 1 September 2026, driving the December CBOT contract to a six-week low near 499 US cents per bushel. EU and Black Sea physical prices remain broadly stable amid ample global supply, with Brazil still shipping large export volumes and China projecting a strong 2026 harvest.
Sunflower oil prices fell for a third consecutive month in September 2026, according to FAO data, as ample Black Sea supply weighs on the market. However, damaged Ukrainian port infrastructure, elevated maritime risk premia, and constrained Russian export routes are cushioning the downturn and keeping volatility high.
Wheat prices in the Rhine region are moving largely sideways heading into Q4 2026 and early 2027, with bread wheat quoted at 240 EUR/t for October–December and only a modest 4–5 EUR/t carry into Q1 2027. Corn and rapeseed are sending stronger price signals, with EU corn commanding a clear premium over feed wheat and rapeseed posting the steepest forward curve in the complex, drawing feed-sector attention away from wheat.
The European Commission has told Ukraine there are no plans to renegotiate its agricultural export quotas, rejecting Kyiv's request for expanded bioethanol access even as Russian strikes continue to damage Ukrainian infrastructure and constrain its exports.
Ukrainian wheat prices remain depressed but stable as Black Sea export logistics keep volumes well below capacity, while German feed wheat trades sideways at elevated levels. The discount of Ukrainian origins to Western European benchmarks is expected to persist into early October 2026.
Ukrainian corn FOB and FCA prices at Odesa edged lower on 24 September 2026 as active Black Sea export flows kept seller competition intense, while French FOB corn firmed and German EXW values held broadly steady. CMB News expects mostly stable to mildly softer indications across Brazil, Germany and Ukraine over the next three days.
The Philippine Department of Agriculture is reviewing broader use of millet in animal feed rations to reduce the country's dependence on corn as a very strong El Niño, projected to persist into the first half of 2027, raises the risk of drought-related supply shocks. While corn remains the dominant feed grain, any large-scale millet adoption could gradually temper growth in Philippine corn import demand, a development international exporters are beginning to monitor.
U.S. grain futures on September 25, 2026 finished near session highs after early selling pressure gave way to a recovery driven by a weaker dollar and trade-deal optimism. December corn edged up fractionally, November soybeans posted weekly gains on news of a U.S.-China trade subset agreement, while wheat futures ended the week lower amid a sustained price downtrend. Persistent Midwest rains are delaying harvest and tightening soybean supplies at processors.
Grain and oilseed futures closed mostly lower on 22 September 2026, according to ADM Investor Services analyst Mark Soderberg. Corn drifted back toward session lows while managed money extended a long position that ADMIS described as a potential record high. Soybeans finished mixed, soybean meal protein value reached a seven-month high, and wheat futures fell sharply amid ongoing Black Sea conflict and softening global supply signals.