Loading…
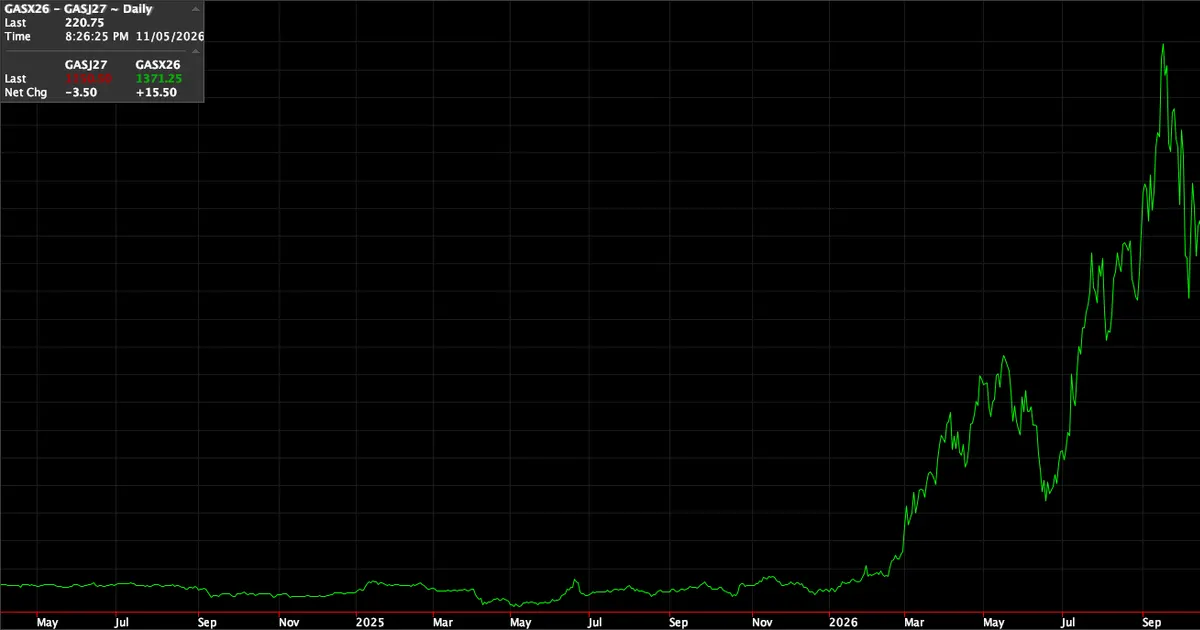
Crude and distillate prices rebounded nearly 4% after a sharp post-election decline, while the November-April ICE gasoil spread widened to $220.75 per tonne. US diesel stocks fell below the 100-million-barrel operational minimum to their lowest since May 2003, and Chinese commercial diesel inventories reached a multi-year low near 1.05 million tonnes in October.
Hormuz shipping disruptions and higher insurance and freight costs are also raising the cost of Gulf crude deliveries.
Low inventories in two major economies and constrained, costly Gulf shipments tighten the distillate balance and support diesel and crude prices. Higher energy costs can also raise feed production and transport expenses.
 globalbiodiesel.comHenri BardonNov 5, 2026
After 250 past bullish geopolitics events, ULSD / Diesel moved a median +1.7% over 5 sessions (58% higher; middle half -3.6% to +8.7%), and +0.9% over 20.
After 626 past bullish geopolitics events, Crude Oil (WTI) moved a median +2.1% over 5 sessions (62% higher; middle half -2.3% to +8.5%), and +1.6% over 20.
After 656 past bullish geopolitics events, Crude Oil (Brent) moved a median +1.9% over 5 sessions (63% higher; middle half -2.7% to +6.6%), and +0.7% over 20.
After 80 past geopolitics events, Palm Oil moved a median +1.2% over 5 sessions (66% higher; middle half -0.9% to +5.2%), and +2.9% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
