Soybean futures and products on the Chicago Board of Trade are undergoing modest profit-taking after a strong late-summer rally, with US September 1 inventories running about 3% below last year and Chinese demand continuing to underpin prices across the complex.
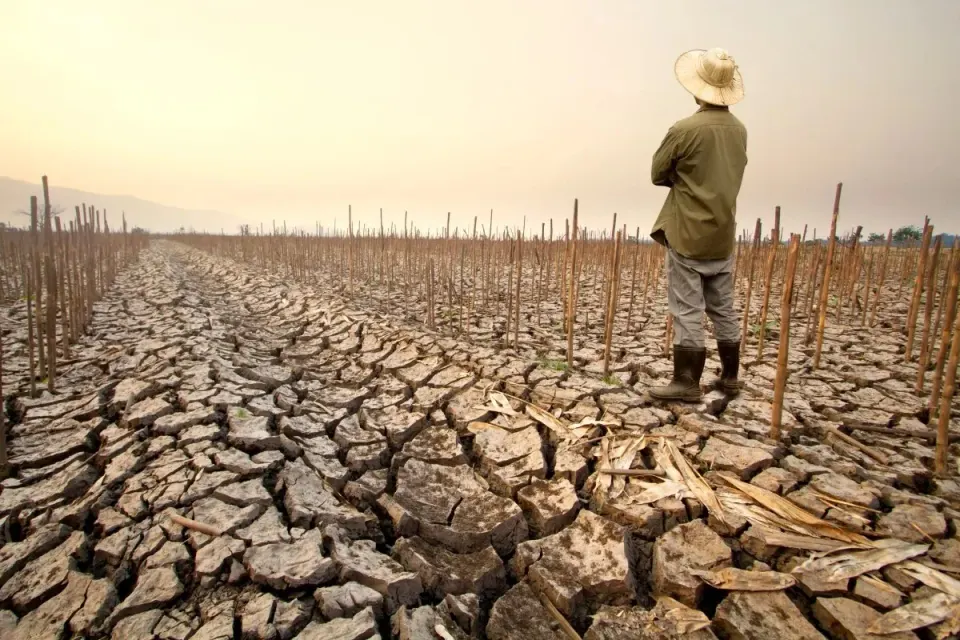
A strengthening El Niño event, combined with fertilizer shortages, geopolitical tensions, and elevated energy costs, could push global food and feed commodity prices up by 14–16%, according to procurement consultancy Beroe. Key feed ingredients including corn, vegetable oils, and sugar face varying levels of supply and price risk, with the full market impact potentially not materialising until 2028.
CBOT soybean futures eased modestly on 23 September 2026, with soybean oil leading declines and meal outperforming, as traders consolidated recent gains ahead of a key U.S.–China diplomatic summit. Ukrainian FOB prices slipped while basis held firm on below-average yields and Black Sea risk. China's August soybean imports remained historically large but showed a 12% year-on-year drop from the U.S., highlighting continued origin diversification. Early South American planting began under a wetter pattern, introducing mild bearish signals for new-crop supply.
MDEX palm oil futures posted modest gains on 23 September 2026, with the nearby October 2026 contract settling at MYR 4,640 per tonne. A gently upward-sloping forward curve reflects competing pressures: elevated Malaysian inventories and soft exports on the bearish side, against Indonesia's imminent B50 biodiesel mandate and drier-than-normal regional weather on the supportive side.
Argentina's bumper 2025/26 corn harvest of roughly 71.7 million tonnes is driving record export volumes to North Africa, displacing Ukrainian and EU supplies constrained by Black Sea disruptions and drought. Morocco, Egypt, and Algeria have all sharply increased purchases from Argentina in the first seven months of 2026, while Brazil's expanding ethanol sector is further tightening global export availability.