Loading…
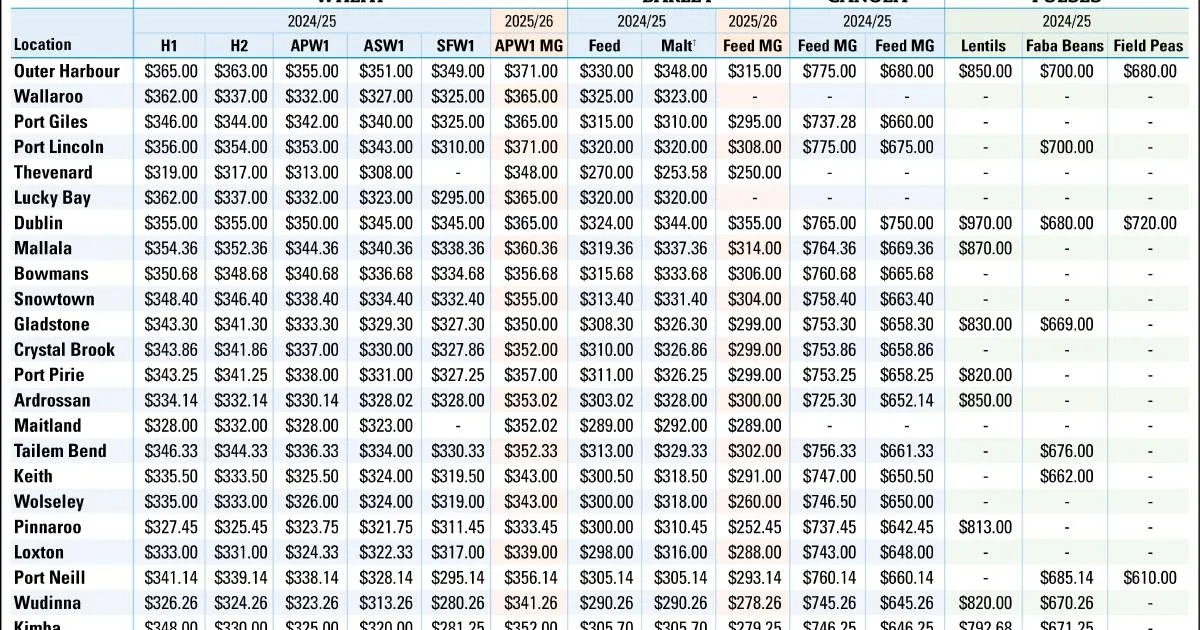
Global rapeseed prices were volatile in March, with EU prices testing two-year highs on tight stocks after a smaller 2024 crop. Canadian canola fell in early March on fears of a US tariff on Canadian canola, and palm oil prices were supported by Malaysian output losses and Indonesian biofuel mandates.
EU 2025-26 rapeseed production is forecast up 12.4%.
A projected EU recovery in rapeseed output and US tariff risk weigh on oilseed meal prices, while tight palm oil supply supports vegetable oil and meal alternatives.
 stockjournal.com.auEd Scamps, Cloudbreak Grain MarketingApr 11, 2025
Not enough comparable past events yet for a historical read.
After 181 past bullish weather events, Palm Oil moved a median +0.5% over 5 sessions (56% higher; middle half -0.9% to +1.9%), and +0.3% over 20.
After 184 past bullish weather events, Soybean Oil moved a median +0.3% over 5 sessions (53% higher; middle half -1.9% to +2.4%), and -0.5% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
