Loading…
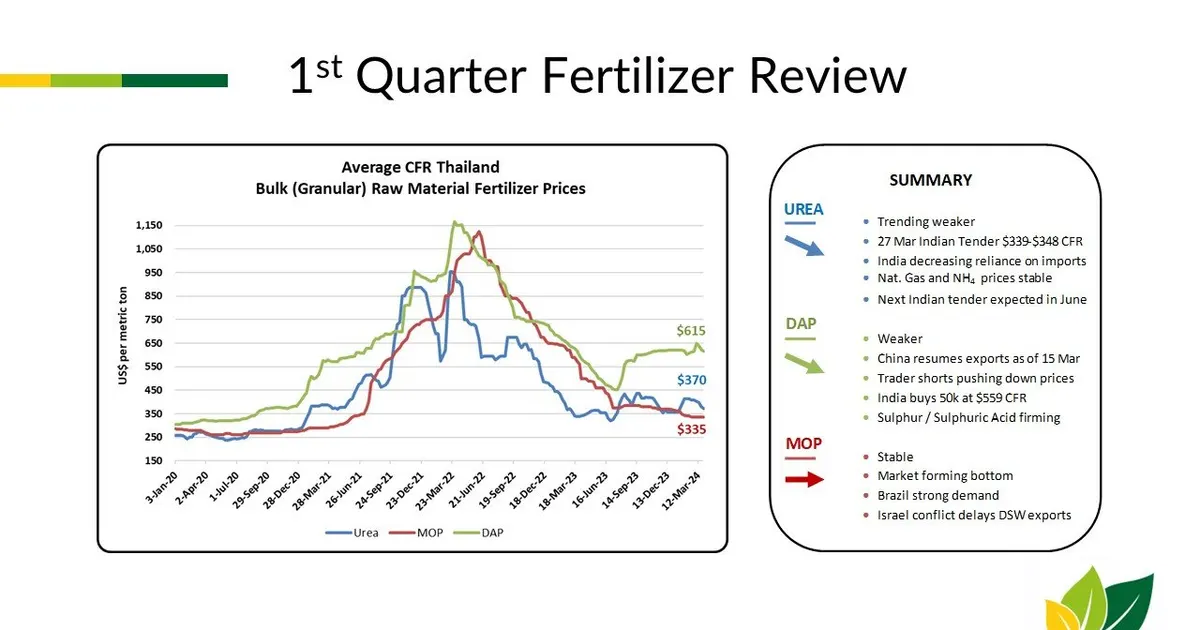
Urea ended Q1 2024 at $372/t CFR, up 4.2% on the quarter, after a February rally to $415 CFR Thailand, but prices then fell in March and broke key support. China lifted its DAP export halt as of March 15, with NPK exports expected to resume May 1 and urea in June.
India's March 27 tender bought 760k tons at $339-348/t CFR.
Resumption of Chinese export flows and steady Indian tender volumes add supply, and sellers expect softer urea and DAP prices until Southeast Asian demand picks up.
 chewachem.comMark LeonardApr 5, 2024
After 81 past bearish trade events, Urea moved a median -1.0% over 5 sessions (28% higher; middle half -7.2% to +0.4%), and -5.5% over 20.
After 40 past bearish trade events, DAP moved a median -0.1% over 5 sessions (38% higher; middle half -3.7% to +0.5%), and -2.4% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
China lifting its DAP export halt from March 15 and expected resumption of other fertilizer exports adds global supply, pressuring DAP prices in the window ending April 5.
China lifting its DAP export halt as of March 15 adds expected supply, a bearish supply-side factor that fits a sharp DAP drop in early April.
Urea prices fell in March and broke key support, the India tender bought only 760k t at $339-348/t CFR, and Chinese urea exports are expected to resume in June, all bearish.
