India Monsoon Deficit Tightens Maize Outlook as Black Sea and EU Corn Prices Soften
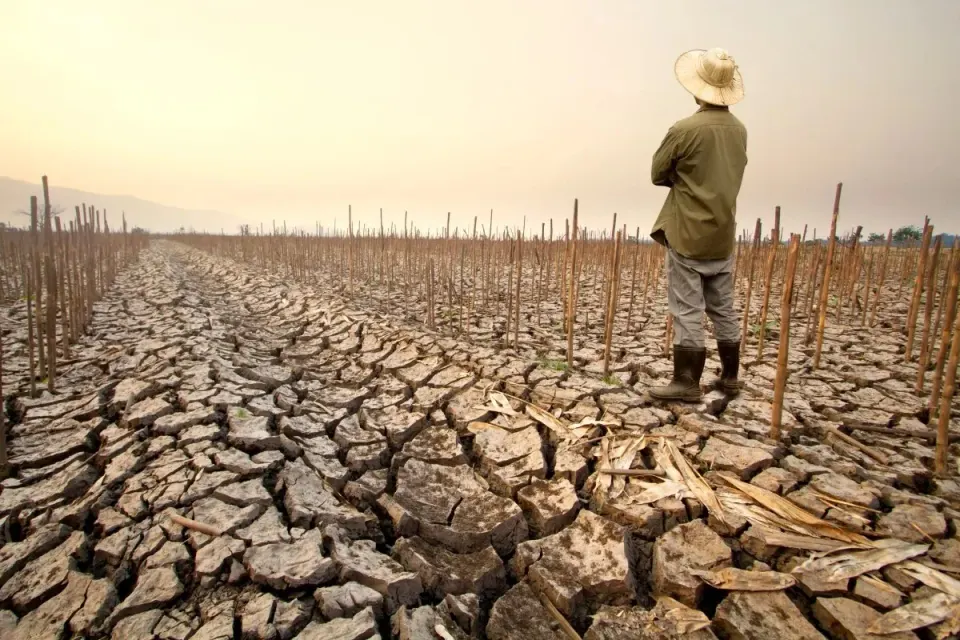
India's 2026 southwest monsoon has fallen roughly 15% below normal, reducing kharif maize sowings by around 2.2% and raising domestic supply concerns. Meanwhile, Ukrainian and EU corn prices have eased, keeping global feed grain markets broadly soft despite the weather-driven uncertainty in South Asia.
India's below-normal monsoon season and a contraction in kharif maize area are tightening domestic supply expectations for the 2026–27 crop year, even as global corn prices remain under pressure from comfortable Black Sea and European Union availabilities, according to CMB News.
India's total kharif crop area stood at approximately 110.39 million hectares as of mid-September, about 1.3% below the prior year, with maize sowings down around 2.2%. The country recorded a seasonal rainfall deficit of approximately 15% between 1 June and 18 September, leaving rainfed maize-growing belts reliant on late-season showers. CMB News noted that maize is among the crops most vulnerable to this season's shortfall, alongside cotton, groundnut and soybean.
With kharif crops moving through late vegetative and grain-filling stages, yield outcomes rather than planted area will determine the final supply picture. CMB News reported that forecasters have warned a strong El Niño pattern could sustain drier conditions into late September for several maize-growing states, limiting the prospect of recovery.
On international markets, Ukrainian feed-grade corn (14% moisture maximum, 98% purity) was quoted at 0.165 EUR/kg CPT Odesa on 17 September, down from 0.172 EUR/kg a week earlier, while FOB corn ex-Odesa stood at 0.159 EUR/kg. In the EU, German feed corn (14% moisture, EXW Drentwede) was reported at 0.295 EUR/kg and French yellow corn at 0.25 EUR/kg FOB Paris. These levels reflect what CMB News described as a "broadly soft to sideways global corn price environment despite India's weather issues."
By contrast, Indian organic starch-grade corn remained quoted at 1.3 EUR/kg FOB New Delhi, unchanged in recent updates. CMB News attributed this divergence to regional quality segments and logistics, noting that premium industrial and organic categories in India remain insulated while bulk feed markets in the Black Sea and EU reflect competitive export pressure.
CMB News indicated that international futures have stayed rangebound in recent sessions, reflecting a balance between regional weather stress in India and comfortable overall global availability. The publication suggested that for feed buyers, basis and freight differentials—rather than flat price surges—are likely to be the main variables in the near term.
Should Indian yields disappoint, CMB News noted the balance of risks has shifted toward a tighter domestic supply scenario, potentially increasing import interest in select segments and firming FOB values for Black Sea and EU exporters, particularly for non-GMO and higher-quality parcels.
Prepared with AI assistance and reviewed by the editorial team.