Loading…
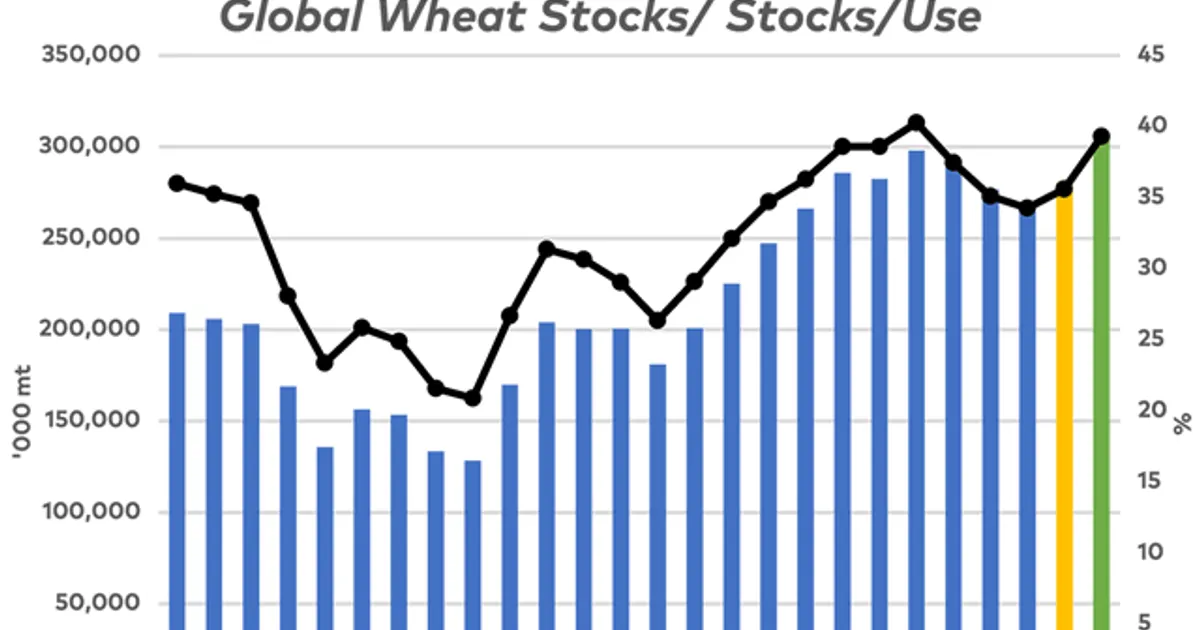
AMIS data show global wheat ending stocks for 2022-23 at 268.4 million tonnes in USDA estimates, the lowest in six years, versus 280.6 mmt from the IGC and 305.4 mmt from AMIS. US wheat futures settled mixed on February 2, with HRW and HRS lower and SRW modestly higher.
Tight global wheat stocks, especially in USDA's estimate, support wheat prices and raise costs for feed buyers relying on wheat in rations.
 dtnpf.comCliff JamiesonFeb 2, 2023
After 769 past bullish report events, WHEAT moved a median +0.2% over 5 sessions (53% higher; middle half -1.4% to +2.0%), and +0.2% over 20.
After 180 past bullish report events, KWHEAT moved a median +0.4% over 5 sessions (53% higher; middle half -2.1% to +3.7%), and -0.6% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
