Loading…
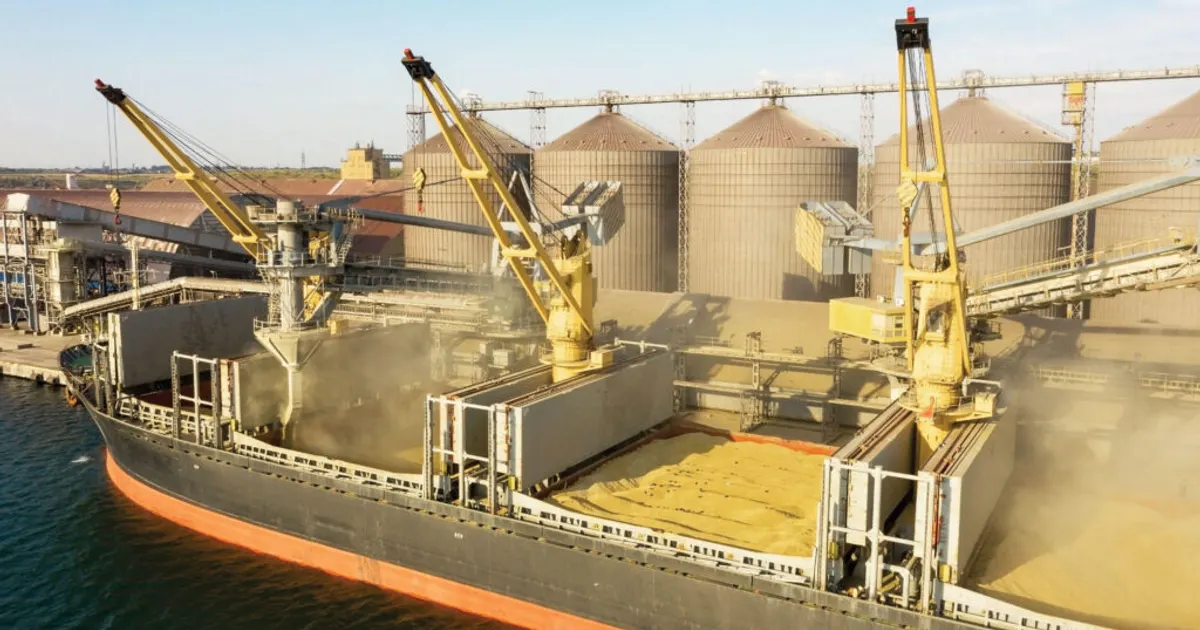
London wheat futures reached a contract high of £208/t on 26 August. The IGC cut its global wheat production forecast by 4m tonnes to 817m tonnes, with deep-sea exports from Russia and Ukraine effectively at a standstill.
Heat has also worsened EU crop outlooks, and EU maize yield estimates were cut.
Lower world output and stalled Black Sea shipments tighten exportable supplies, raising wheat and maize costs for feed buyers. Importers are shifting to Romanian and Baltic origins, which supports prices in those markets.
 fwi.co.ukPhilip CaseAug 27, 2026
After 361 past bullish geopolitics events, Wheat (SRW) moved a median +0.7% over 5 sessions (58% higher; middle half -1.4% to +3.7%), and +1.3% over 20.
After 323 past bullish geopolitics events, Corn moved a median +0.5% over 5 sessions (57% higher; middle half -1.5% to +2.9%), and +0.9% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
