Loading…
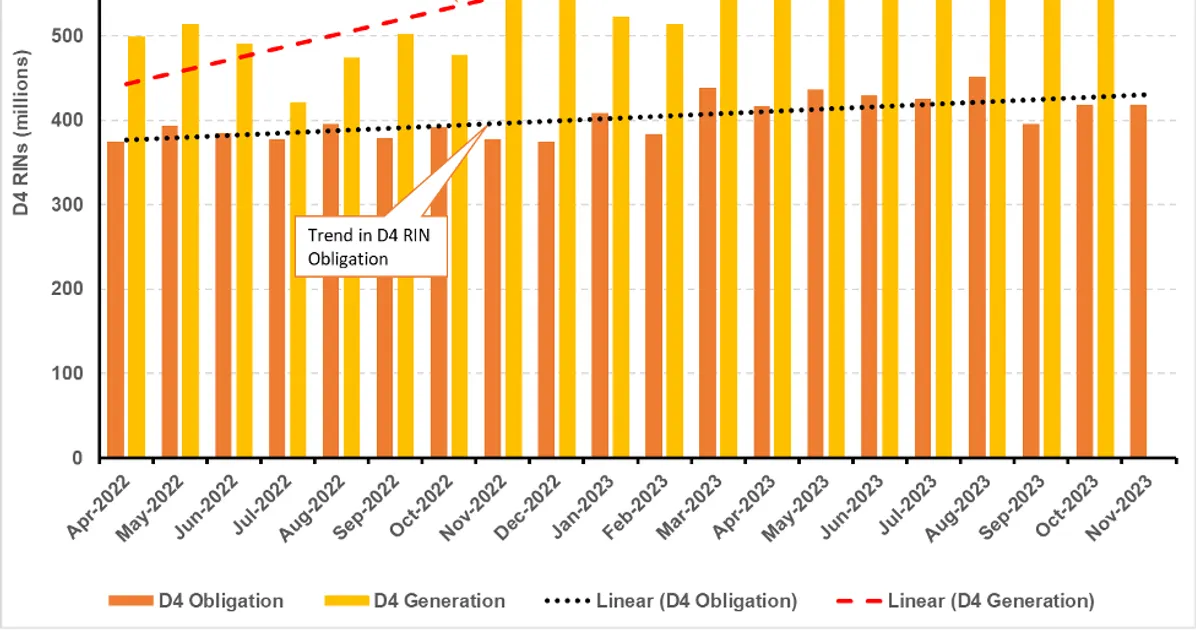
D4 RIN generation is growing faster than the D4 renewable volume obligation due to continued expansion of US renewable diesel production. Analysis is updated with the latest EIA and EPA data, and the trend is expected to continue into 2024 as more capacity completes.
Rising D4 RIN supply pressures RIN prices and reduces the incentive to crush for biofuel, which weighs on soybean oil demand expectations. Growing renewable diesel output keeps soybean oil feedstock demand firm.
 stillwaterassociates.comScottNov 29, 2023
After 351 past bearish policy events, Soybean Oil moved a median -0.0% over 5 sessions (49% higher; middle half -1.7% to +1.8%), and -0.2% over 20.
After 27 past neutral policy events, ULSD / Diesel moved a median -1.4% over 5 sessions (41% higher; middle half -4.3% to +2.6%), and -4.6% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
