Loading…
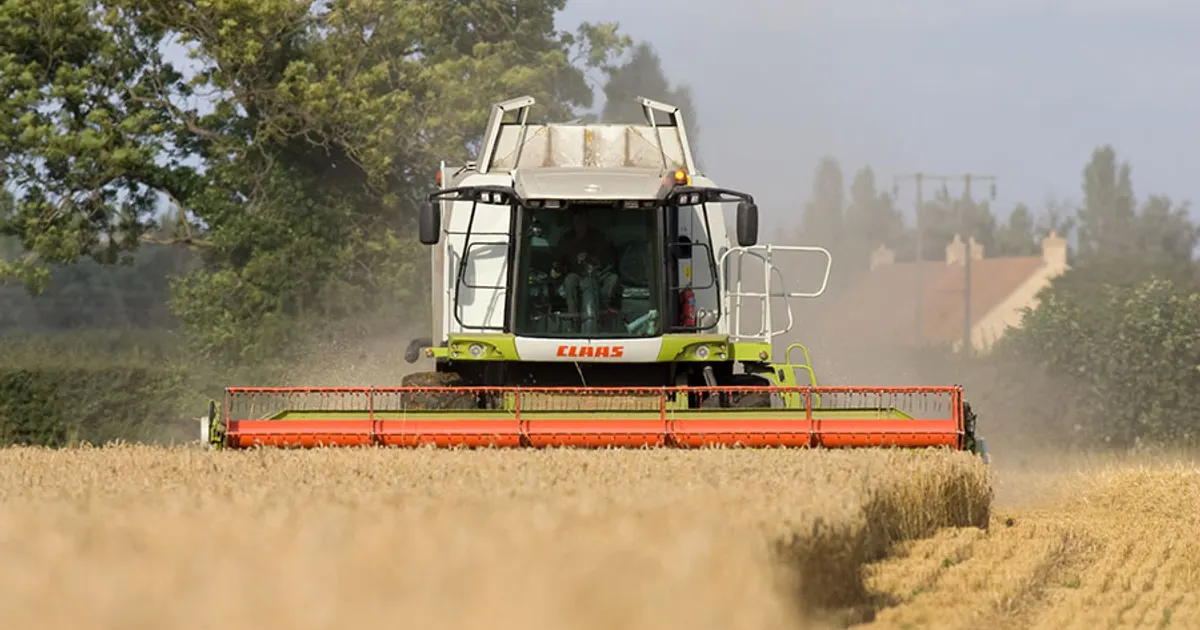
The IGC cut its world wheat production estimate by 16 million tonnes to 721 million, versus 758 million last year, citing lower yields in the Black Sea and EU. World grain output is forecast at a three-year low of 2.059 billion tonnes, and the world will again consume more grain than it produces.
Ex-farm UK wheat and barley prices rose sharply over the prior 10 days.
A second year of consumption exceeding production drains stocks and supports feed grain prices, with further downgrades possible.
 fwi.co.ukSuzie HorneJul 27, 2018
After 769 past bullish report events, Wheat (SRW) moved a median +0.2% over 5 sessions (53% higher; middle half -1.4% to +2.0%), and +0.2% over 20.
Not enough comparable past events yet for a historical read.
After 1,040 past bullish report events, Corn moved a median +0.5% over 5 sessions (62% higher; middle half -0.9% to +2.0%), and +0.8% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
