Loading…
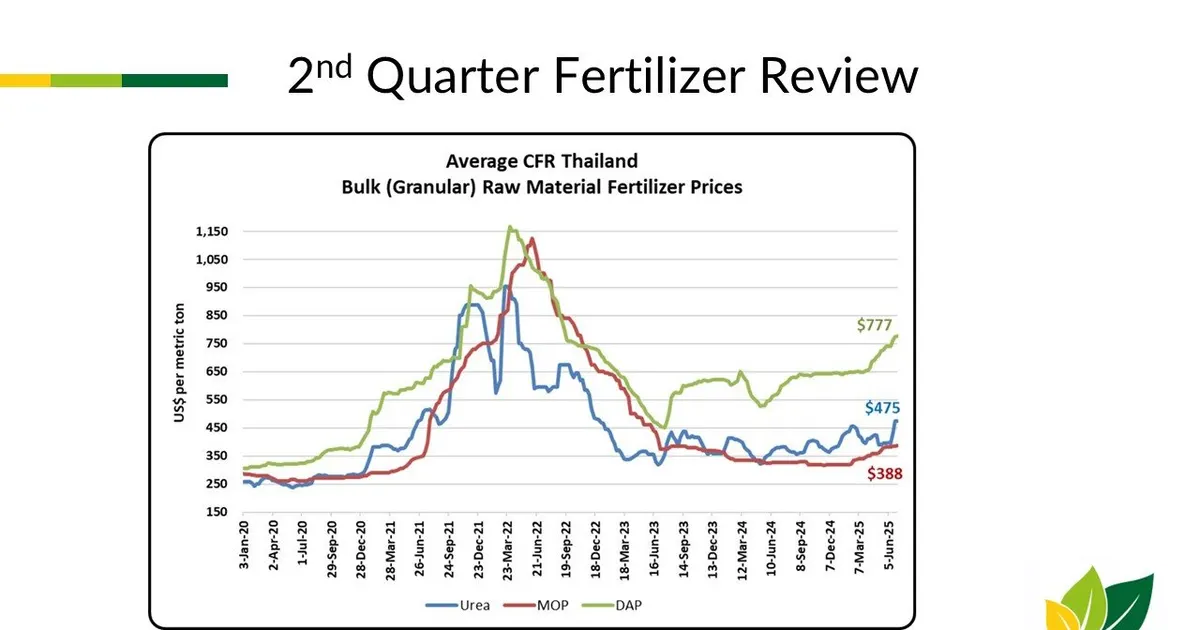
A Q2 2025 fertilizer review cites the Israel-Iran conflict and Strait of Hormuz risk, Egyptian urea output disruptions from LNG shortages, and EU tariffs on Russian and Belarusian fertilizers. It reports urea prices up 16%, DAP up 19%, and MOP up 11% in the quarter.
Supply risks in the Gulf and Egypt, plus new EU tariffs, are tightening nitrogen and phosphate availability. Higher fertilizer prices raise farmers' input costs and can shift feed grain planting and margins.
 chewachem.comMark LeonardJul 11, 2025
After 205 past bullish geopolitics events, Urea moved a median +0.4% over 5 sessions (53% higher; middle half -2.1% to +3.0%), and -0.4% over 20.
After 114 past bullish geopolitics events, DAP moved a median +0.0% over 5 sessions (50% higher; middle half -0.3% to +1.2%), and +0.3% over 20.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
