Loading…
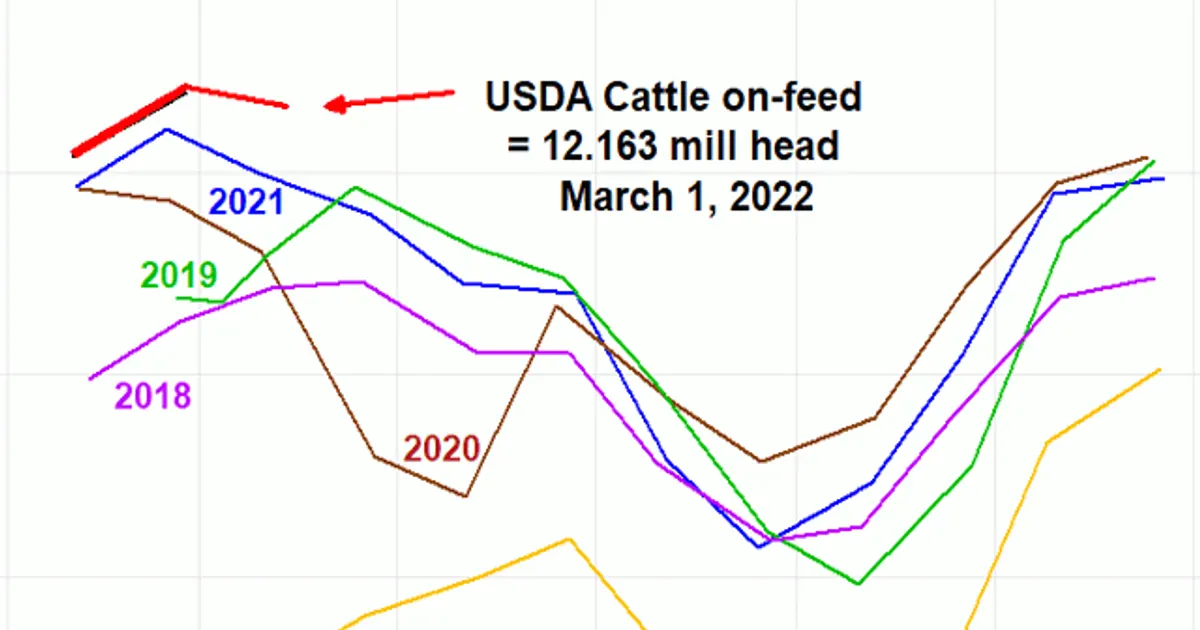
USDA NASS reported cattle on feed for feedlots of 1,000+ head at 12.2 million on March 1, 2022, up 1% from a year earlier and the highest March 1 inventory since 1996. February placements rose 9% to 1.85 million head, and marketings rose 5% to 1.83 million head.
Heavier feedlot supplies and strong placements add near-term fed cattle supply, which is bearish for cash and futures prices. Drought-driven placements also bear on future marketing.
 dtnpf.comDTN StaffMar 28, 2022
After 144 past bearish report events, LCATTLE moved a median -0.1% over 5 sessions (49% higher; middle half -1.1% to +0.9%), and +0.5% over 20.
After 126 past bearish report events, FCATTLE moved a median +0.1% over 5 sessions (52% higher; middle half -1.3% to +2.0%), and +0.6% over 20.
After 770 past neutral report events, CORN moved a median +0.2% over 5 sessions (54% higher; middle half -1.1% to +1.6%), and +0.7% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
