Loading…
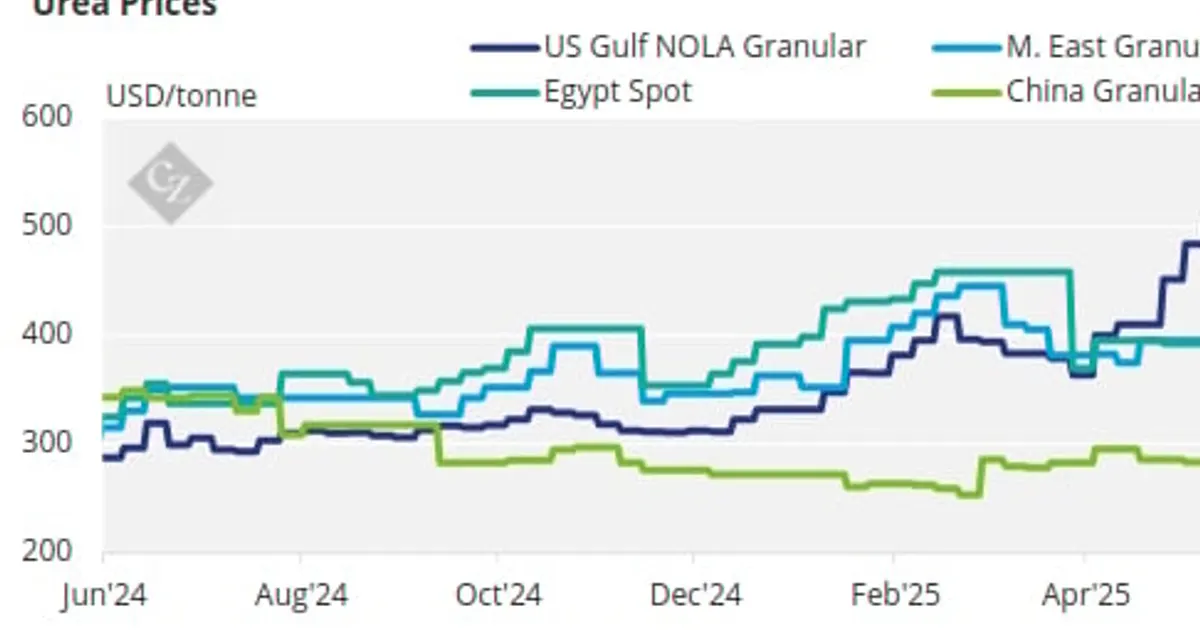
Urea supply remains disrupted after the Middle East conflict began on 13 June, with Egyptian plants running at 50-60% capacity and Iranian production halted. Oman's SIUCI sold August cargoes at USD495-525/tonne FOB, and Southeast Asian tenders cleared around USD452-470/tonne FOB.
US Gulf prices fell in the off-season, while Brazil's buying season approaches.
Reduced output from Egypt and Iran, together with approaching Brazilian demand, is likely to firm urea prices and raise nitrogen input costs for grain and feed producers.
 van.nongnghiepmoitruong.vnH.DJul 3, 2025
After 205 past bullish geopolitics events, UREA moved a median +0.4% over 5 sessions (53% higher; middle half -2.1% to +3.0%), and -0.4% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
