Loading…
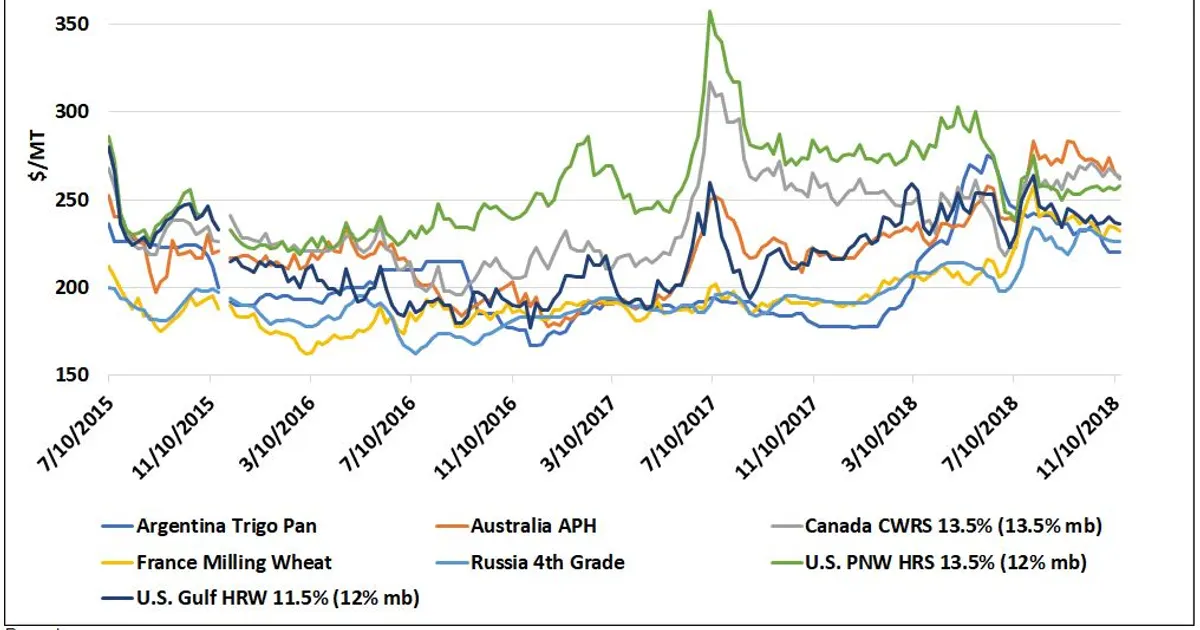
IGC data shows U.S. wheat now offers better value than major competitor origins as of Nov. 22, with SRW at $216/MT, $10 below Russian 4th Grade.
Shrinking high-quality supplies in Australia, the EU, Russia and Ukraine have lifted their export prices while U.S. fob prices slipped about 8%.
Price convergence is pulling import demand toward U.S. wheat from price-sensitive buyers, which supports U.S. wheat export prices and feed-wheat competitiveness versus corn.
 uswheat.orgNov 27, 2018
After 431 past bullish trade events, Wheat (SRW) moved a median +0.0% over 5 sessions (50% higher; middle half -1.3% to +2.1%), and +0.5% over 20.
After 683 past bearish trade events, Corn moved a median -0.2% over 5 sessions (47% higher; middle half -1.7% to +1.6%), and +0.3% over 20.
After 102 past bullish trade events, Wheat (HRW) moved a median 0.0% over 5 sessions (49% higher; middle half -2.0% to +3.5%), and -1.4% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
