Loading…
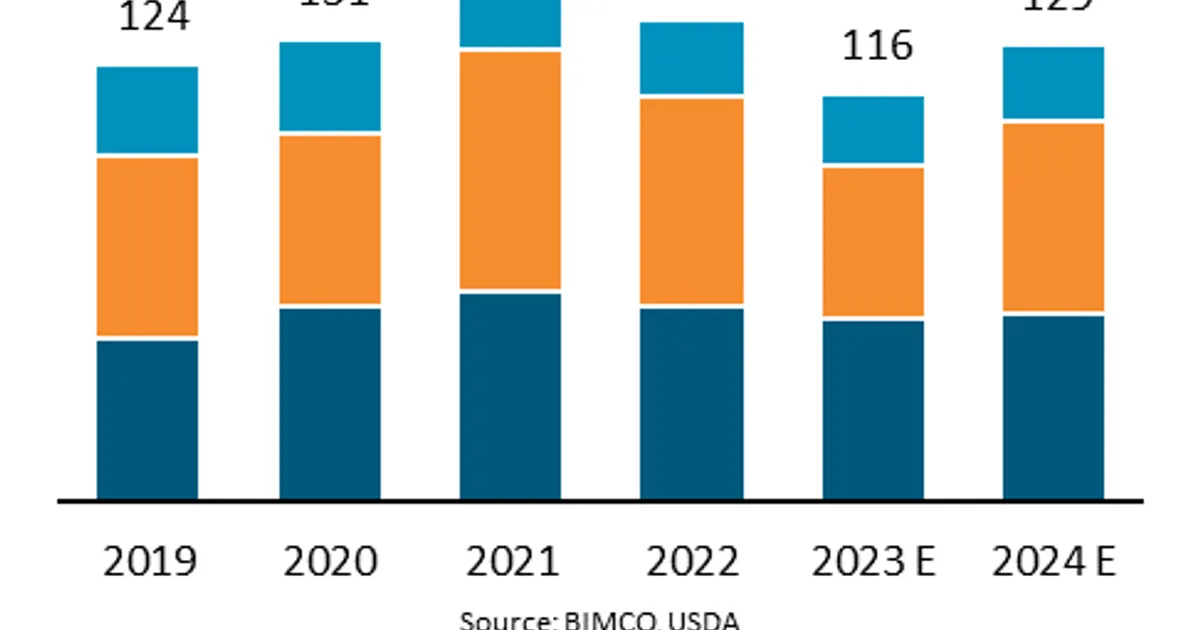
BIMCO reports that US soybean, maize and wheat exports could fall 15% in 2023 after drought cut 2022 harvests, with a recovery expected from Q4 as the US maize harvest comes in. Global grain shipments are estimated down 4% y/y in the first seven months of 2023, and Panamax earnings are at their weakest July since 2016.
Lower US export volumes and weak grain shipments keep Panamax freight rates depressed, while Brazilian maize and soybean exports partly offset the gap. Lower US grain availability for export is mildly supportive for competing origins' prices.
 ilnautilus.itRedazioneJul 20, 2023
After 729 past bullish trade events, Corn moved a median +0.4% over 5 sessions (56% higher; middle half -1.1% to +1.8%), and +0.5% over 20.
After 696 past bullish trade events, Soybeans moved a median +0.3% over 5 sessions (54% higher; middle half -1.3% to +1.9%), and +0.7% over 20.
After 431 past bullish trade events, Wheat (SRW) moved a median +0.0% over 5 sessions (50% higher; middle half -1.3% to +2.1%), and +0.5% over 20.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
