Loading…
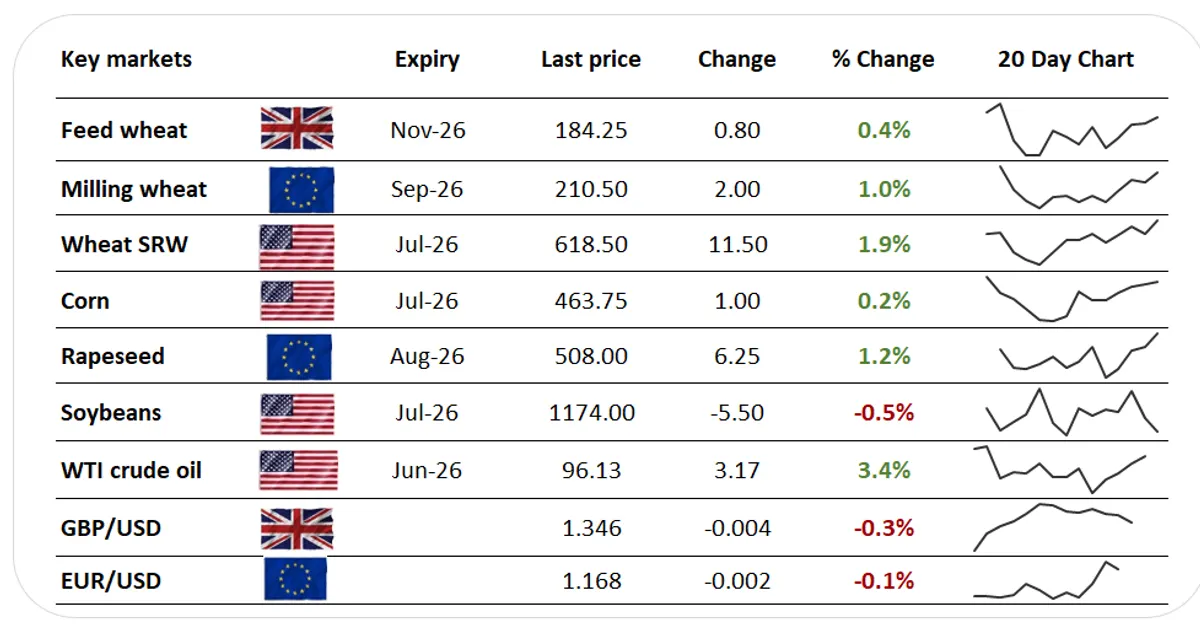
Wheat prices extended their rally as US drought spread, with USDA reporting about 70% of US winter wheat in drought. The International Grains Council cut its forecasts for US and Australian 2026 wheat harvests, and hard red winter wheat reached a 22-month high.
Saudi Arabia also issued a tender for 710,000 tonnes of wheat.
Lower US and Australian crop forecasts reduce exportable wheat supplies, supporting prices. Hard red winter strength feeds into the broader wheat complex that feed buyers pay for.
 crmagri.comMike VerdinApr 23, 2026
After 322 past bullish weather events, Wheat (HRW) moved a median -0.1% over 5 sessions (49% higher; middle half -2.5% to +3.2%), and +1.0% over 20.
After 1,072 past bullish weather events, Wheat (SRW) moved a median +0.2% over 5 sessions (55% higher; middle half -1.4% to +2.3%), and +0.3% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
Drought covering ~70% of winter wheat, IGC cuts to US and Australian crops and a 22-month HRW high tightened supply expectations; Saudi tender added demand.
