Loading…
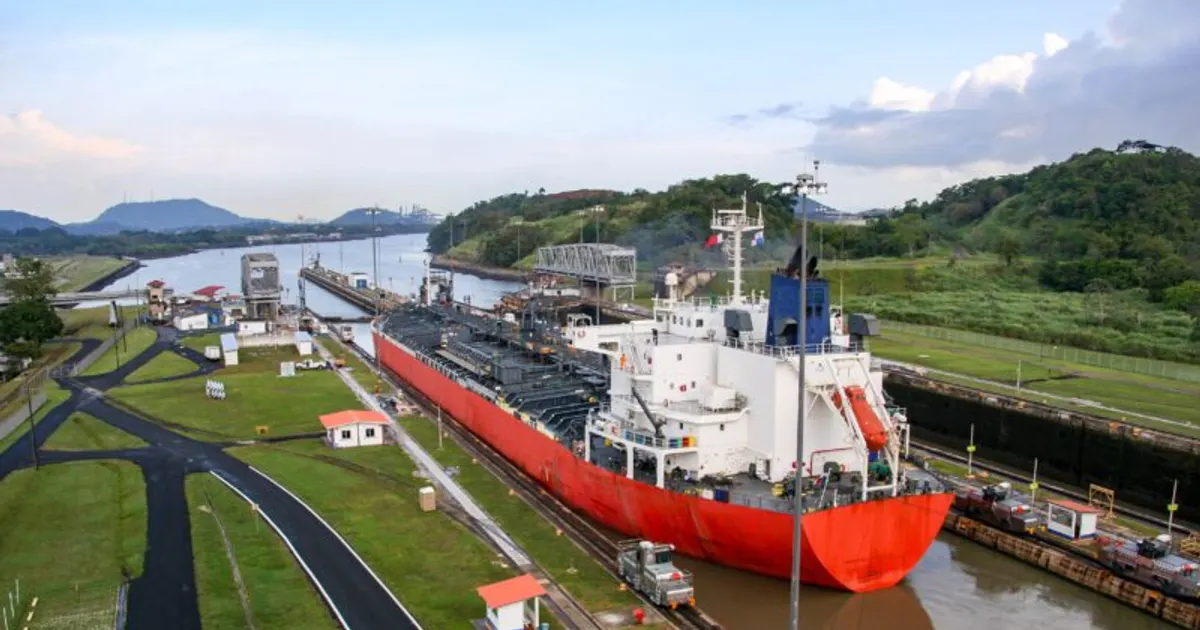
BIMCO reports Panama Canal ship capacity from September 2024 to January 2025 was 10% below the 2019-2022 average, even though drought transit restrictions have been lifted. Dry bulk, LNG and some tanker traffic has not returned, and U.S. grain shipments have shifted to West Coast ports.
Containerships, LPG carriers and car carriers are running above historical levels.
Ships avoiding the canal lengthen voyages and raise tonne-mile demand, which supports freight rates. The shift of U.S. grain exports to Pacific ports also reduces Gulf canal flows and can change regional basis levels.
 gcaptain.comMike SchulerFeb 6, 2025
Not enough comparable past events yet for a historical read.
After 284 past neutral logistics events, Corn moved a median -0.0% over 5 sessions (49% higher; middle half -1.3% to +1.4%), and -0.2% over 20.
After 230 past neutral logistics events, Soybeans moved a median +0.4% over 5 sessions (55% higher; middle half -1.4% to +2.0%), and +0.1% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
