Loading…
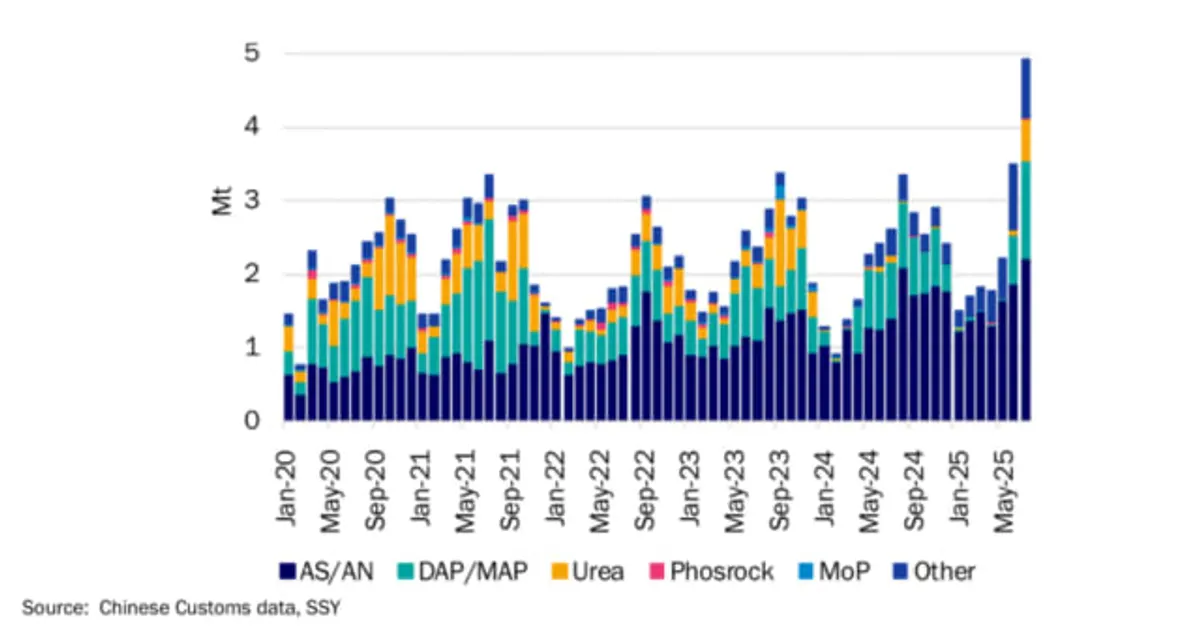
Fertiliser prices have reached multi-year highs, with China halting exports to India and Chinese fertiliser shipments in July hitting decade-high levels. US NOLA urea peaked at $455/st in May before easing to $400/st in September, and DAP and potash prices were sharply higher year-on-year.
Chinese DAP/MAP exports restarted in June, with July volumes at a three-year high of 1.3 Mt.
Chinese export policy and Middle East gas outages are the key swing factors for nitrogen and phosphate prices. Higher fertilizer costs raise the production cost of feed grains and oilseeds, and cumulative Chinese phosphate exports remain well below last year.
 ssyglobal.comSSYSep 23, 2025
After 23 past neutral trade events, Urea moved a median 0.0% over 5 sessions (48% higher; middle half -1.1% to +1.0%), and +2.8% over 20.
After 193 past bullish trade events, DAP moved a median +0.4% over 5 sessions (54% higher; middle half -0.3% to +1.8%), and +1.9% over 20.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
