Loading…
 FEEDSOFTAIFEEDSOFTAI
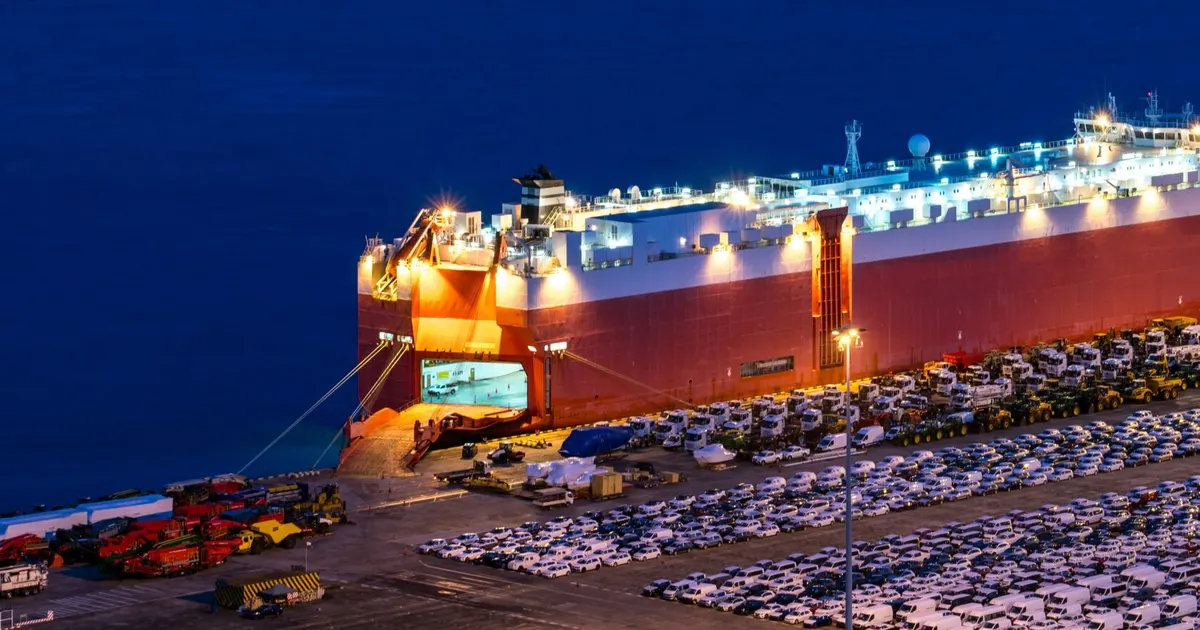
Clarksons data shows the six-to-twelve-month timecharter rate for a 6,500 ceu car carrier reached USD 100,000 per day in November, the third consecutive month of increases. Suezmax and Aframax spot earnings fell more than 20% week-over-week, while one-year timecharter rates for tankers and VLGCs remained far above 2025 averages.
Hormuz disruption and attack damage are removing tankers from the market, keeping shipping costs elevated and adding freight cost pressure on bulk and feed imports. Lower freight could revive long-haul crude and LPG demand, but the overall freight outlook stays firm.
 maritimefinance.euTheaNov 20, 2026
After 11 past neutral logistics events, Crude Oil (WTI) moved a median +3.8% over 5 sessions (73% higher; middle half -0.4% to +6.6%), and +6.3% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.