Loading…
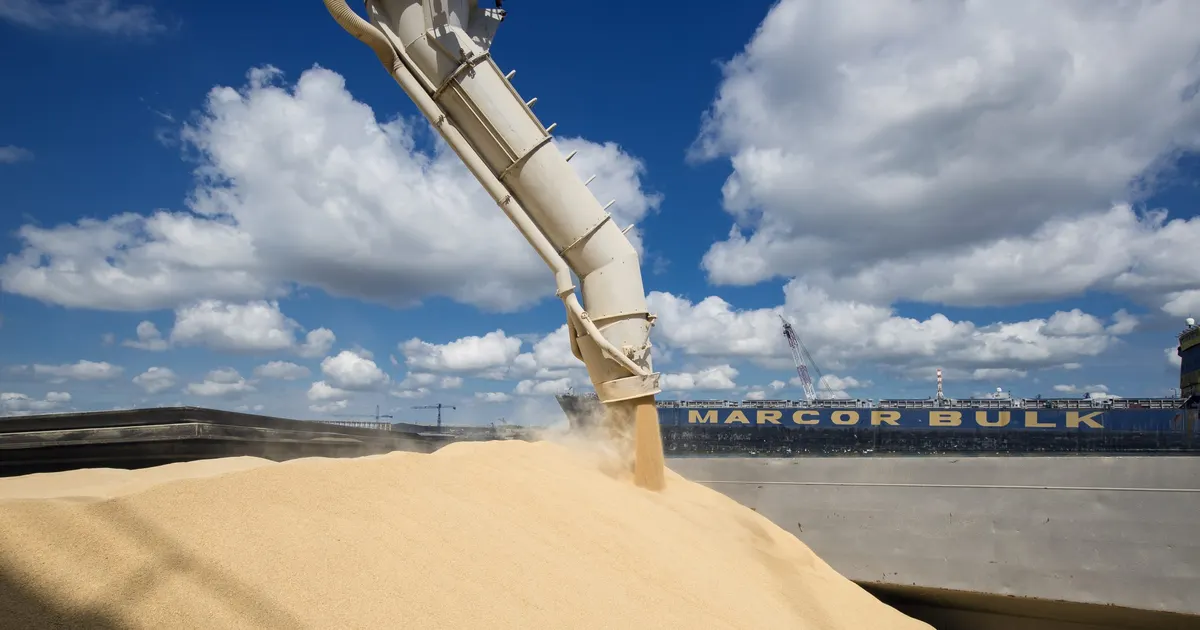
FAO forecasts global cereal production of about 2.979 billion tonnes in 2026, while international cereal trade is projected to fall 3.5% to 505.8 million tonnes in 2026/27. Black Sea shipping constraints, limited alternative transport capacity and changing export availability are shifting sourcing and shipment arrangements; the IGC also projects lower wheat and coarse-grain trade.
Reduced trade and constrained export routes can limit accessible supplies despite high global production, supporting freight costs and export-region grain prices. Shifting origins may also complicate procurement and delivery planning for feed buyers.
 controlunion.comNov 11, 2026
After 283 past bullish logistics events, Wheat (SRW) moved a median -0.2% over 5 sessions (46% higher; middle half -1.4% to +1.3%), and -0.1% over 20.
After 285 past bullish logistics events, Corn moved a median +0.1% over 5 sessions (52% higher; middle half -1.5% to +1.5%), and +0.8% over 20.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
