Loading…
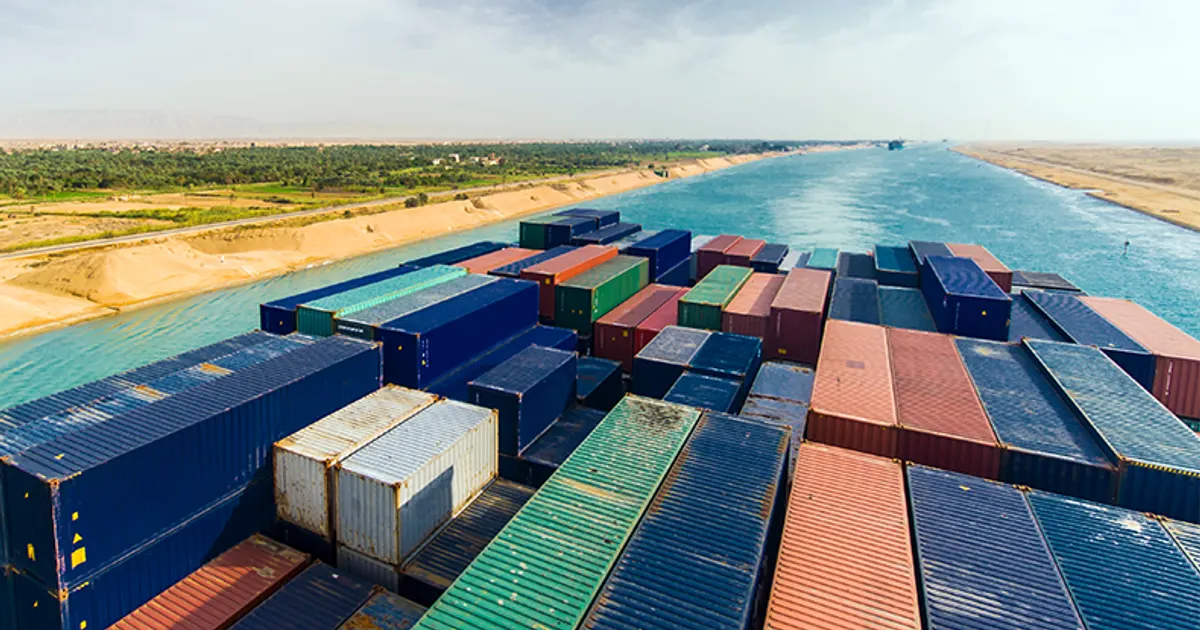
Suez Canal traffic reached 125.6m dwt in October, its highest since shipping left the Red Sea, though still 33% below November 2023 levels. Crude tanker traffic hit 47.13m dwt, above the 44.35m dwt pre-crisis monthly average, driven by Russian crude flows and Saudi use of Yanbu, and sanctioned vessels accounted for 37.7% of large crude tanker transits.
Rerouting around Hormuz and Bab el Mandeb keeps freight costs and transit times elevated, which supports shipping and energy costs for feed ingredient imports. The recovery is driven by disrupted trade flows rather than normalised security, so freight rates are unlikely to ease quickly.
 lloydslist.comRichard Meade, Cichen ShenNov 3, 2026
Not enough comparable past events yet for a historical read.
After 36 past logistics events, BRENT moved a median +0.2% over 5 sessions (50% higher; middle half -4.6% to +3.2%), and +1.5% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
