Loading…
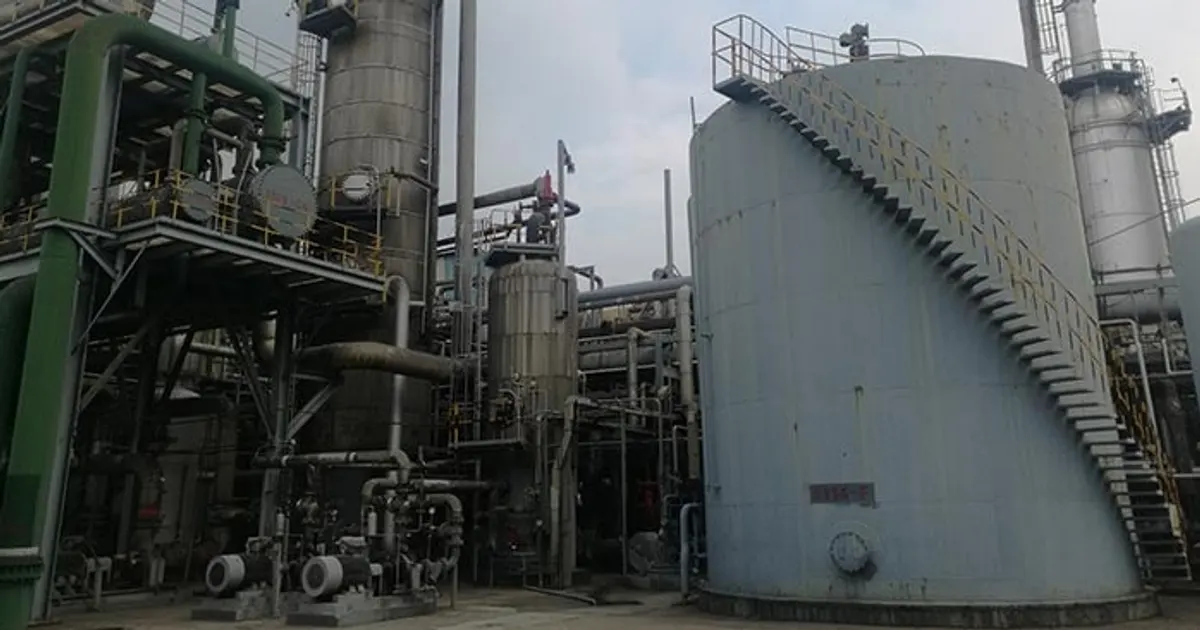
CRU reports that China accounts for 34% of global urea capacity and 10% of global trade in 2019. Chinese nitrogen producers are restructuring as strict environmental rules force closures and winter idling, especially of anthracite coal-based plants.
Chinese marginal exports set the global urea floor price, so shifting coal-based output and closures directly affect supply. Lower-cost bituminous producers are likely to supply marginal tonnes, which shapes the price outlook.
 crugroup.comAuthor Gavin Ju, Keshni SritharanNov 27, 2019
After 26 past neutral policy events, UREA moved a median -1.0% over 5 sessions (27% higher; middle half -4.1% to +0.6%), and -2.5% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
