Loading…
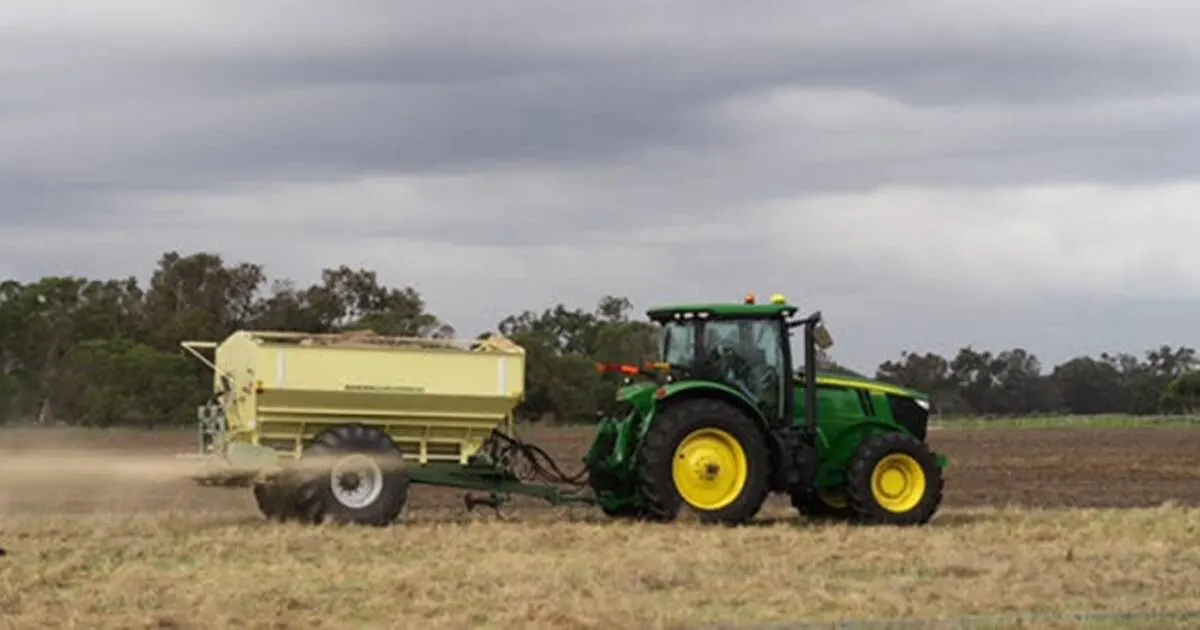
MAP and DAP fertiliser supplies are critically tight in Australia, with some product selling near A$800 a tonne. Causes include China restricting phosphate exports for domestic use, shipping disruption with fewer bulk carriers in service, and higher sulphur and ammonia input costs.
Tight phosphate supply and high input costs raise the cost of crop production and could limit fertiliser application, with supply not expected to ease until later in the year.
 theland.com.auJohn EllicottMar 24, 2021
Not enough comparable past events yet for a historical read.
After 151 past bullish policy events, DAP moved a median +0.0% over 5 sessions (50% higher; middle half -0.6% to +0.9%), and +1.9% over 20.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
