加载中…
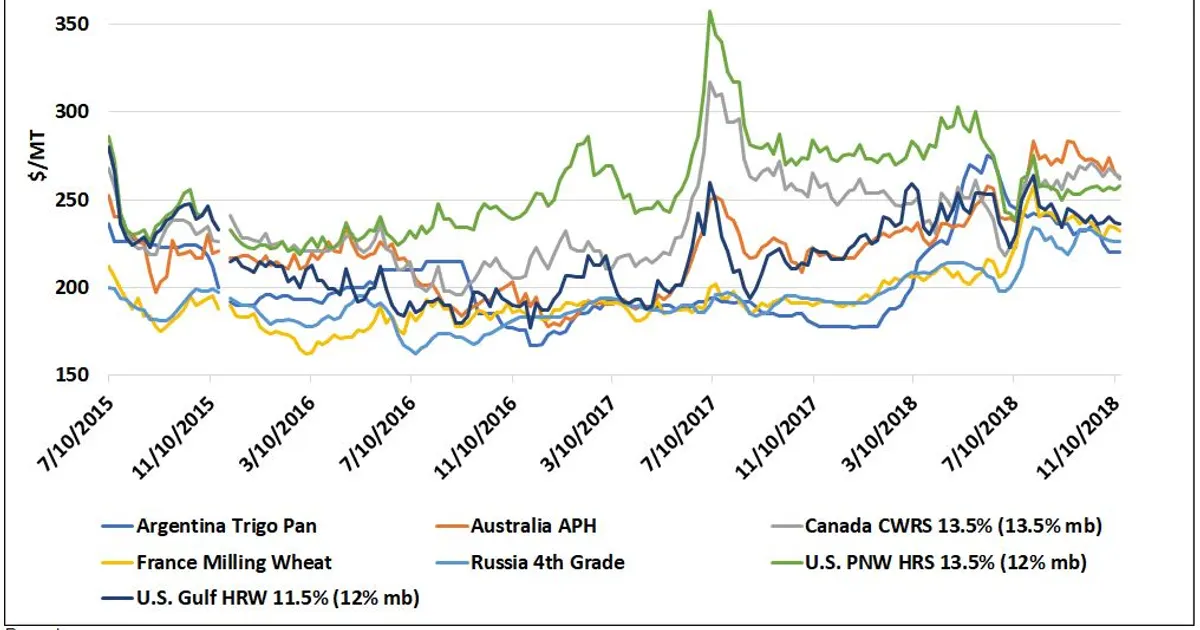
IGC data shows U.S. wheat now offers better value than major competitor origins as of Nov. 22, with SRW at $216/MT, $10 below Russian 4th Grade.
Shrinking high-quality supplies in Australia, the EU, Russia and Ukraine have lifted their export prices while U.S. fob prices slipped about 8%.
Price convergence is pulling import demand toward U.S. wheat from price-sensitive buyers, which supports U.S. wheat export prices and feed-wheat competitiveness versus corn.
 uswheat.org2018年11月27日
在过去 431 次看涨的贸易事件之后,小麦(SRW) 在 5 个交易日内中位数变动 +0.0%(50% 上涨;中间一半区间为 -1.3% 至 +2.1%),20 个交易日内为 +0.5%。
在过去 683 次看跌的贸易事件之后,玉米 在 5 个交易日内中位数变动 -0.2%(47% 上涨;中间一半区间为 -1.7% 至 +1.6%),20 个交易日内为 +0.3%。
在过去 102 次看涨的贸易事件之后,小麦(HRW) 在 5 个交易日内中位数变动 0.0%(49% 上涨;中间一半区间为 -2.0% 至 +3.5%),20 个交易日内为 -1.4%。
各商品基准价相对事件前最后收盘价的变动。历史数据汇总同类过往事件;仅描述已发生的情况,不代表未来走势。不构成投资建议。
