불러오는 중…
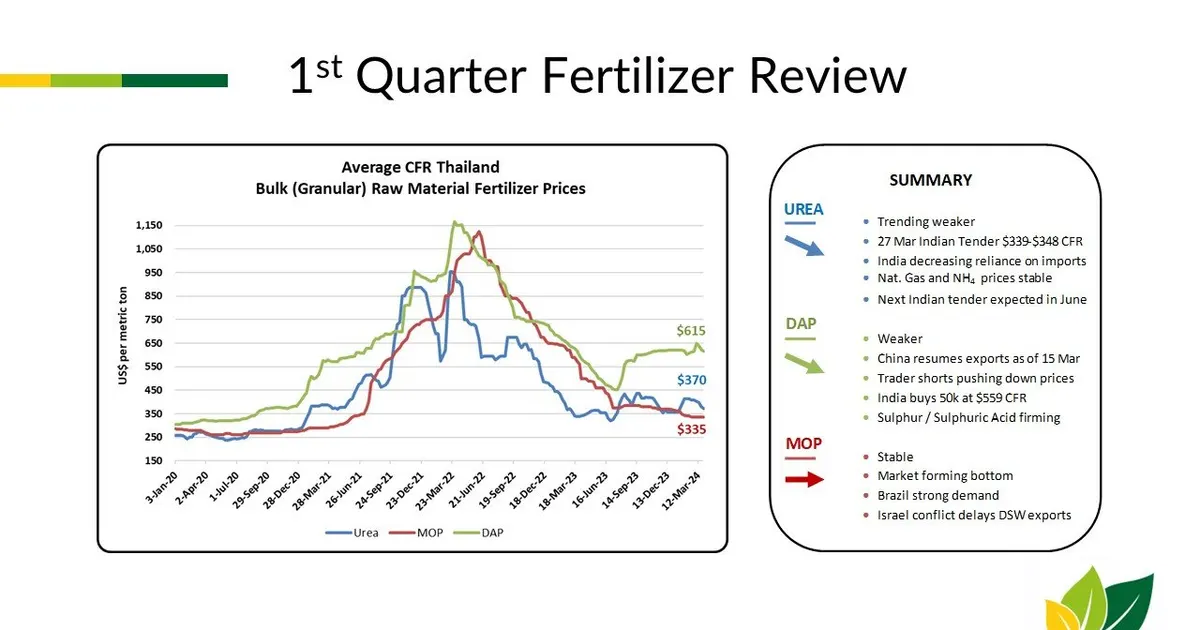
Urea ended Q1 2024 at $372/t CFR, up 4.2% on the quarter, after a February rally to $415 CFR Thailand, but prices then fell in March and broke key support. China lifted its DAP export halt as of March 15, with NPK exports expected to resume May 1 and urea in June.
India's March 27 tender bought 760k tons at $339-348/t CFR.
Resumption of Chinese export flows and steady Indian tender volumes add supply, and sellers expect softer urea and DAP prices until Southeast Asian demand picks up.
 chewachem.comMark Leonard2024. 4. 5.
과거 하락 무역 이벤트 81건 이후, 요소은 5거래일 동안 중앙값 -1.0% 변동(상승 28%; 중간 50% 범위 -7.2%~+0.4%), 20거래일 동안 -5.5%.
과거 하락 무역 이벤트 40건 이후, DAP은 5거래일 동안 중앙값 -0.1% 변동(상승 38%; 중간 50% 범위 -3.7%~+0.5%), 20거래일 동안 -2.4%.
각 품목 벤치마크의 이벤트 직전 종가 대비 변동. 과거 수치는 같은 유형의 과거 이벤트를 합산한 것으로, 일어난 일을 설명할 뿐 앞으로 일어날 일이 아닙니다. 투자 자문이 아닙니다.
China lifting its DAP export halt from March 15 and expected resumption of other fertilizer exports adds global supply, pressuring DAP prices in the window ending April 5.
China lifting its DAP export halt as of March 15 adds expected supply, a bearish supply-side factor that fits a sharp DAP drop in early April.
Urea prices fell in March and broke key support, the India tender bought only 760k t at $339-348/t CFR, and Chinese urea exports are expected to resume in June, all bearish.
