Caricamento…
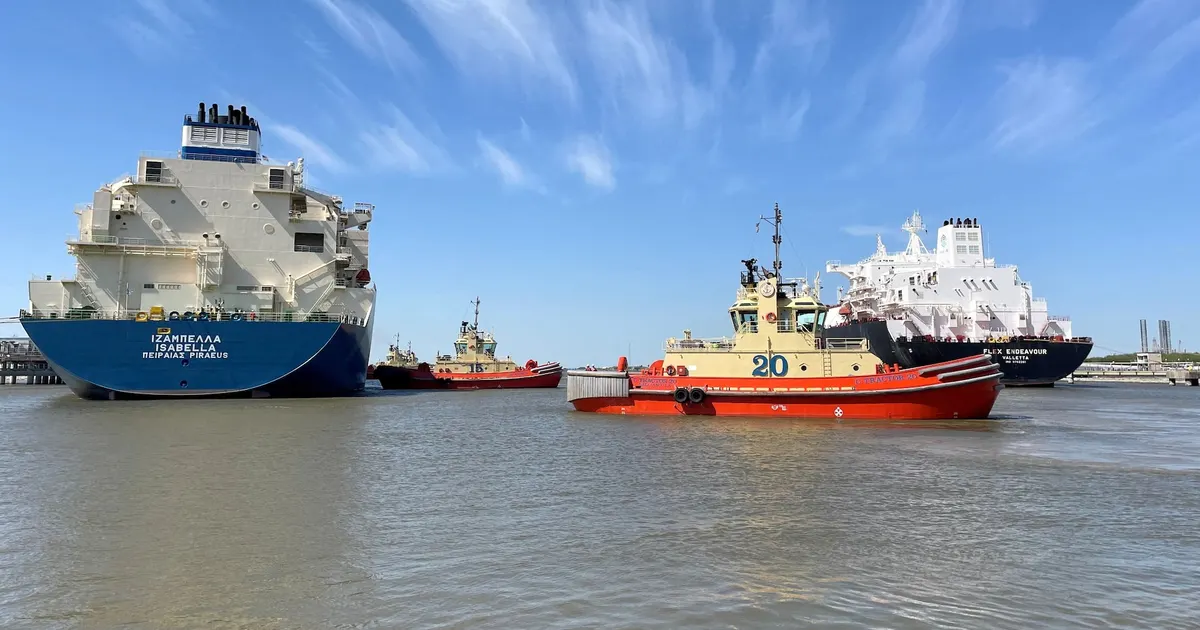
US natural gas demand from LNG export plants is heading for its first annual decline in eight years. The US is the largest LNG exporter and a key supplier to Europe.
European prices remain relatively high as expected US output growth has not materialized.
Weaker LNG feedgas demand reduces pull on US gas supply, which is bearish for domestic gas prices and eases pressure on nitrogen fertilizer costs.
 reuters.comScott Disavino, Curtis Williams20 dic 2024
Dopo 24 eventi commercio ribassista passati, Gas naturale si è mosso in mediana di +2,8% in 5 sedute (54% in rialzo; metà centrale da -4,5% a +7,3%), e di -1,2% in 20.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
