Caricamento…
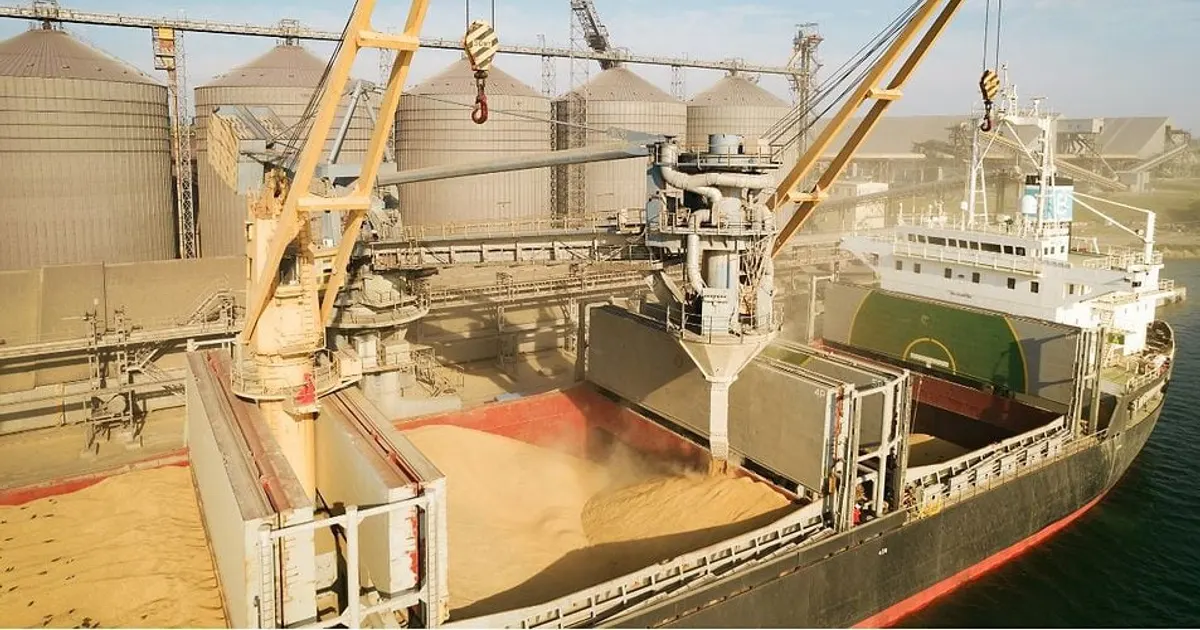
Grain shipping costs have risen sharply in 2026, with the Baltic Dry Index near five-year highs in mid-September and the IGC Grains and Oilseeds Freight Index at 187 points versus 138 in early January. Strong bulk demand, including Chinese iron ore trades, and typhoon disruptions have tightened vessel supply.
Panama Canal transit limits from October, caused by El Niño drought, add further bottlenecks.
Higher freight costs raise landed prices for grain importers and widen the cost gap for US exports routed through Panama, supporting alternative origins. Buyers face higher delivered feed costs.
 world-grain.comMichael King18 set 2026
Ancora troppi pochi eventi passati comparabili per una lettura storica.
Dopo 359 eventi logistica ribassista passati, Mais si è mosso in mediana di -0,3% in 5 sedute (44% in rialzo; metà centrale da -1,5% a +1,5%), e di -0,5% in 20.
Dopo 297 eventi logistica ribassista passati, Soia si è mosso in mediana di +0,3% in 5 sedute (54% in rialzo; metà centrale da -1,5% a +1,8%), e di +0,7% in 20.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
