Loading…
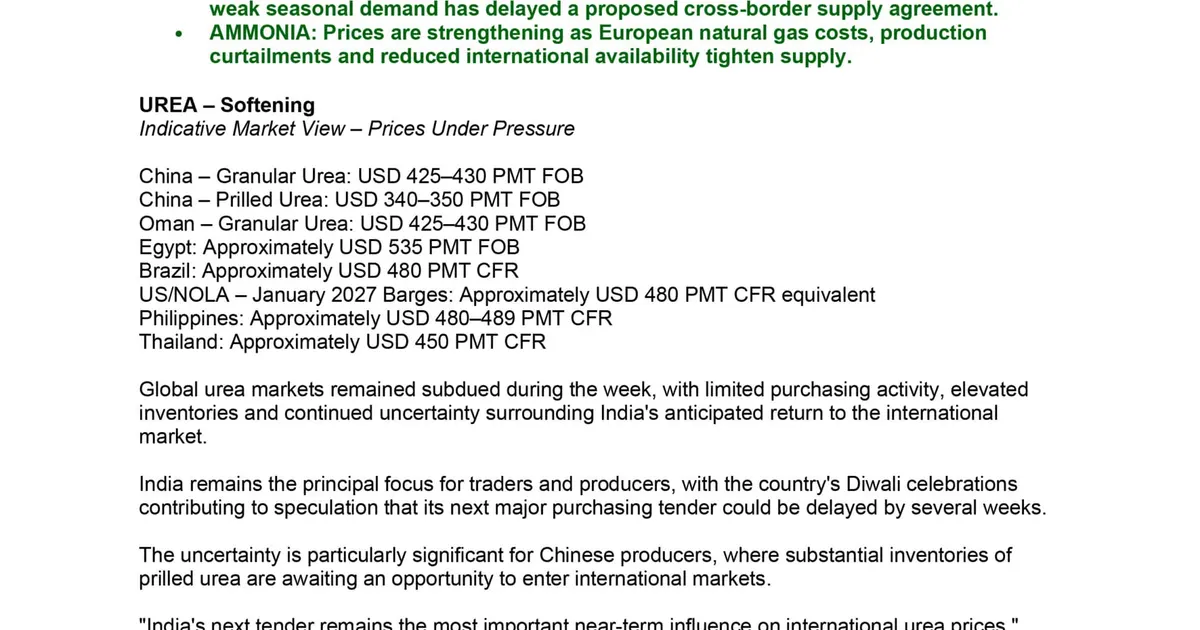
Global urea prices remained under pressure in the week ending 6 November 2026, with China granular urea quoted at USD 425–430 PMT FOB and Brazil around USD 480 PMT CFR. Potash prices were weighed down by high inventories in China and Russia, while processed phosphates faced downward pressure from weak demand.
Ammonia prices strengthened on higher European gas costs and production curtailments.
Lower urea and phosphate prices ease input costs for feed-grain and oilseed growers, but firming ammonia reflects tighter nitrogen supply tied to European gas. India's delayed urea tender remains the key swing factor for global fertiliser prices.
 ausfertcorp.comNov 11, 2026
Not enough comparable past events yet for a historical read.
Not enough comparable past events yet for a historical read.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
