Loading…
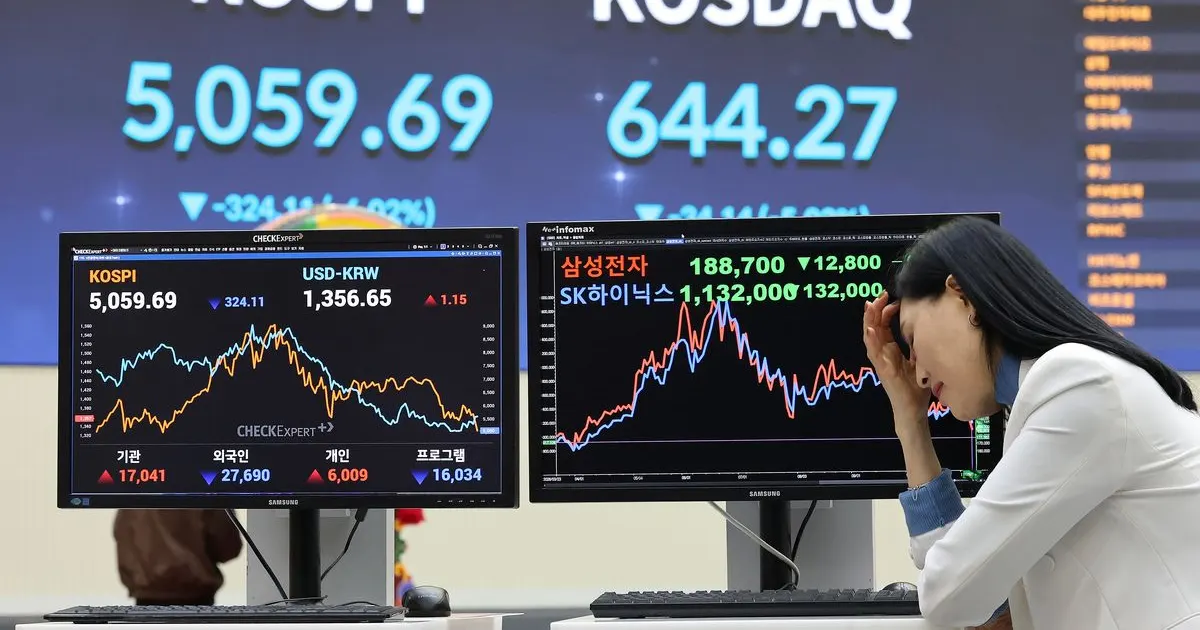
Ahead of its November rate decision, the Bank of Korea faces persistent inflation near 3% alongside concerns that AI investment concerns and a sharp equity selloff could weaken growth. Third-quarter GDP grew 1.0% quarter on quarter, while October headline inflation eased to 2.8% and core inflation remained at 2.8%; expectations for the eventual policy-rate peak have become less certain.
The tension between inflation and weaker growth could affect the timing and extent of Korean rate increases, influencing the won and the cost of dollar-priced imports. The article does not indicate a direct change in feed-commodity supply or demand.
 fnnews.comNov 7, 2026
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
