Loading…
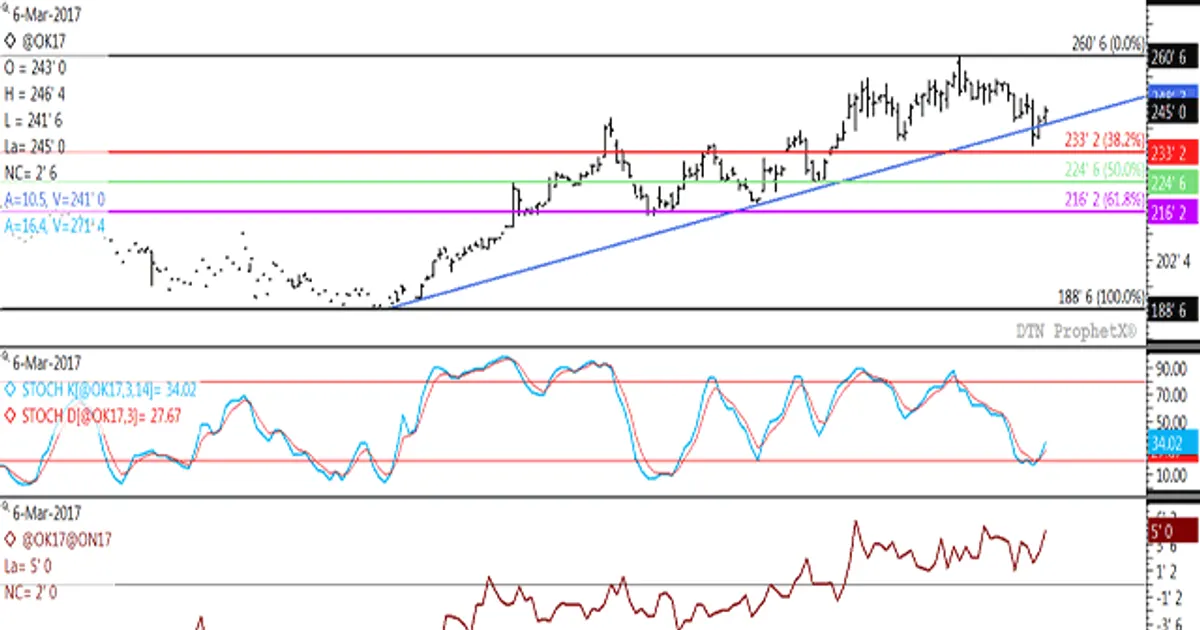
May oats are holding above a trendline drawn from the September contract low after testing a 33% retracement of the move from the September low to the February high. The May/July spread has been inverted since January 18, and noncommercial traders increased their net-long futures position to 554 contracts as of February 28.
An inverted May/July spread signals strong near-term commercial demand for oats, and rising speculative net-long positions add support to prices in the short term.
 dtnpf.comCliff JamiesonMar 6, 2017
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
