Loading…
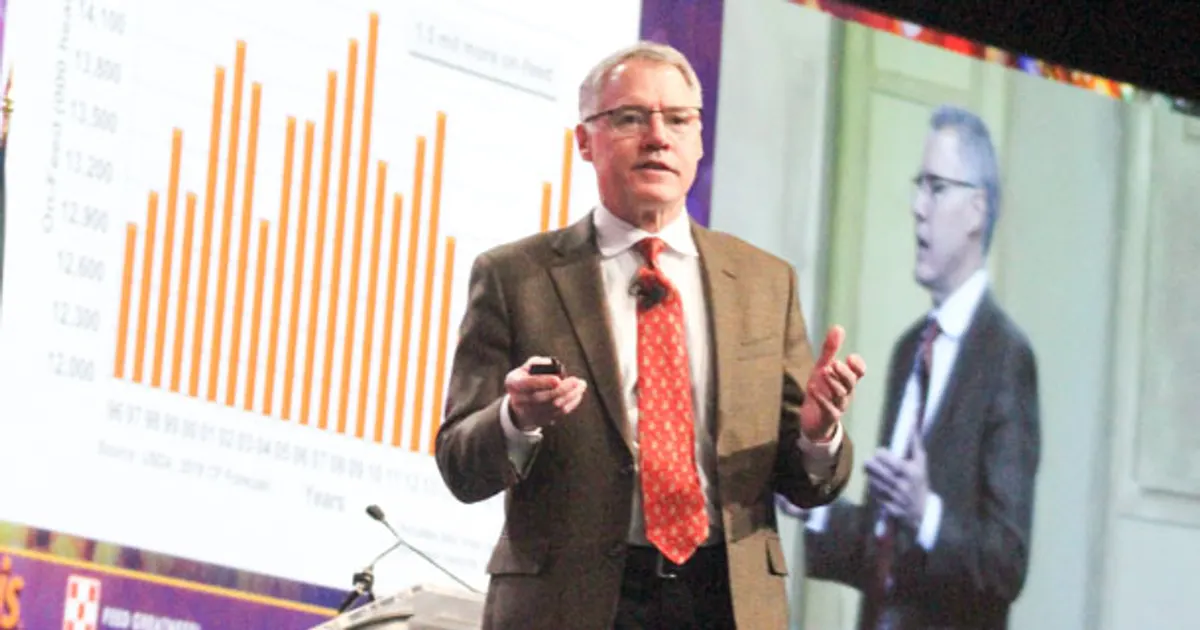
An industry outlook says US fed cattle marketings are up about 3 million head compared with 2015, with feedyards and packing plants running at high capacity. The herd is also up about 3 million head, and the cycle is growing more slowly and steadily.
Analysts expect narrower price spreads between cattle classes.
A fuller cattle pipeline means ample supply and continued cyclical price risk for cow-calf and stocker producers until production peaks later in the decade.
 agproud.comCarrie VeselkaFeb 16, 2019
Not enough comparable past events yet for a historical read.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
