Loading…
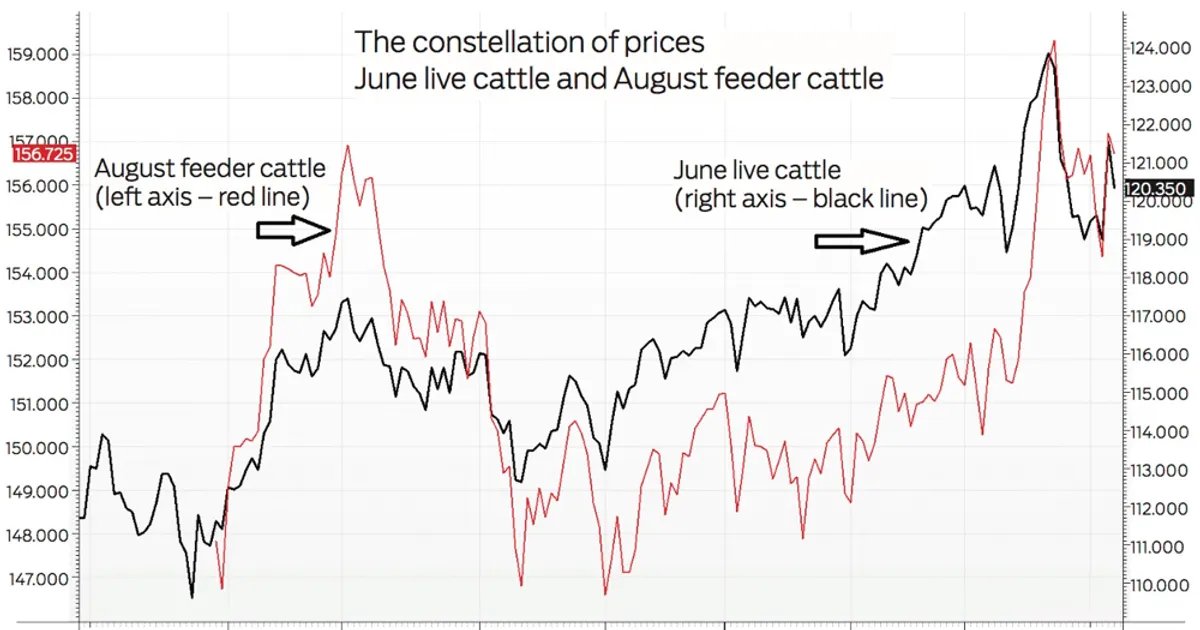
Jerry Klassen explains the constellation of prices, where deferred live cattle and feeder cattle futures move in tandem with nearby live cattle. He notes that Midwest weather has driven volatility and that live cattle futures have traded near 52-week highs on production risk premium.
Understanding how nearby live cattle prices drive deferred and feeder contracts helps buyers and producers time marketing and hedging decisions. The article is educational commentary rather than a new supply or demand shock.
 canadiancattlemen.caJerry KlassenMay 10, 2019
Not enough comparable past events yet for a historical read.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
