Loading…
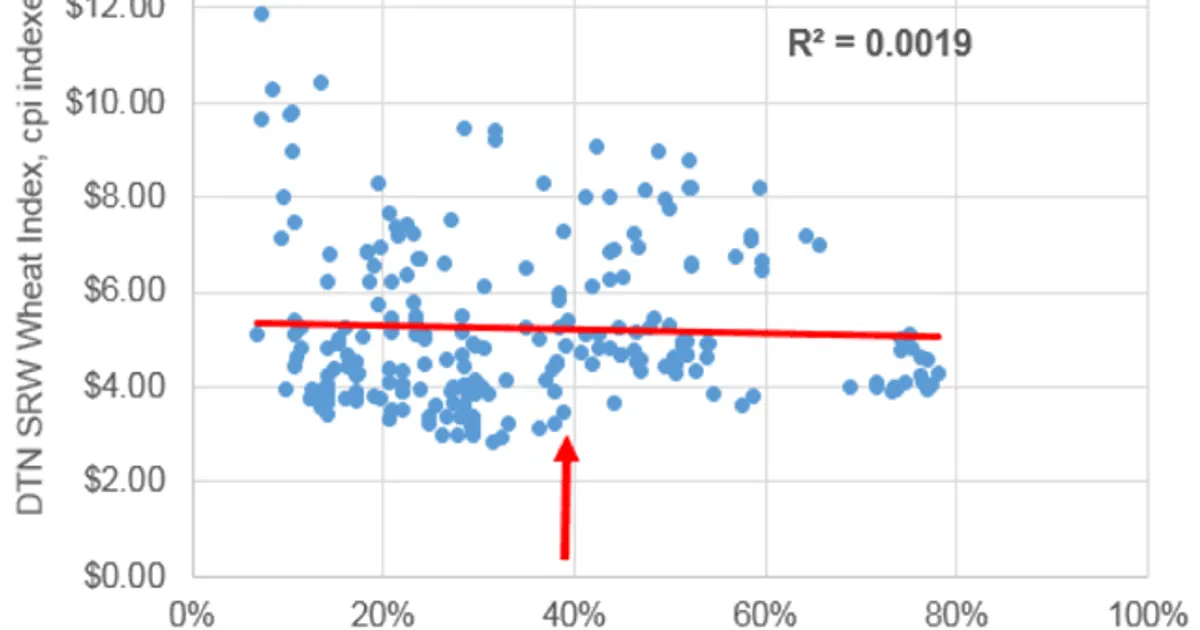
DTN analyst Todd Hultman argues that USDA's projected 39% ending stocks-to-use for U.S. soft red winter wheat in 2019-20 may not drive prices as expected, noting historical correlation between ending stocks and SRW price indices is weak. He contrasts Chicago wheat's heavy trading volume with Kansas City and Minneapolis contracts.
Opinion-based analysis suggests SRW prices may not follow standard supply-demand logic, so buyers should not assume a tight-stocks projection will support prices. The commentary has limited immediate price impact.
 dtnpf.comTodd HultmanAug 23, 2019
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
