Loading…
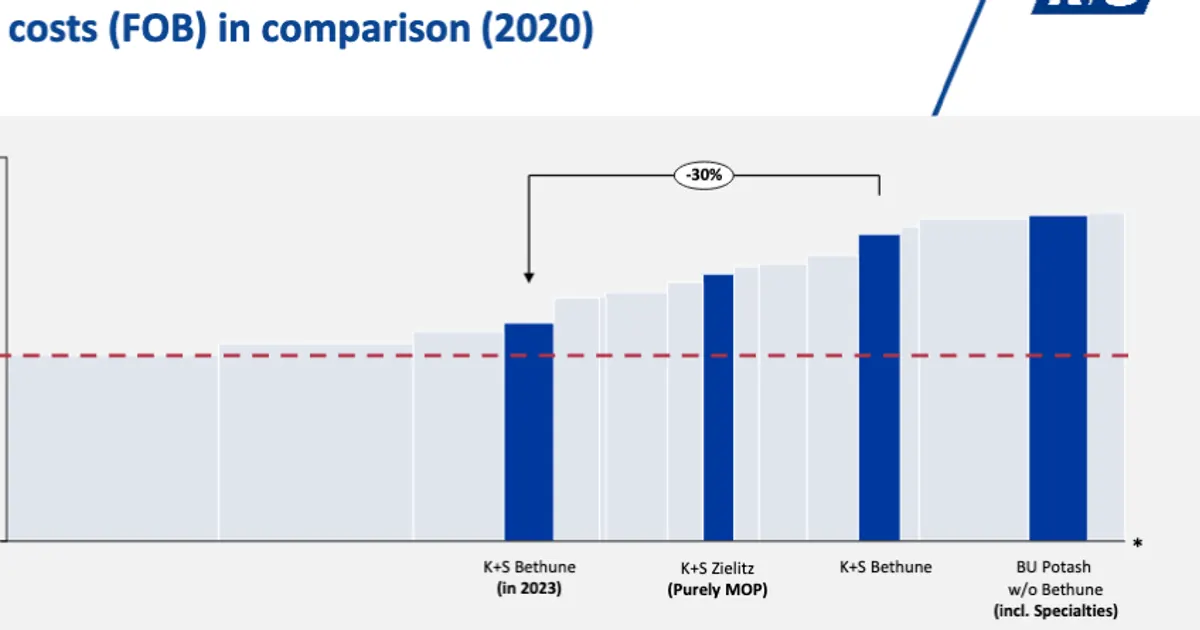
K+S, a German potash producer, is described as the highest-cost scale producer in a potash market expected to enter a multi-year downturn. The author highlights its heavy leverage (4.5x net debt to EBITDA), negative cash flow, and a 835mm bond maturity in 2021 alongside a costly brownfield expansion in Canada.
A prolonged potash price slump would pressure the highest-cost producers first, and a fall of around 15% could push output and pricing lower across the sector. Weaker potash prices lower fertilizer costs for farmers, which can support crop margins over time.
 rapercapital.com/ puppyehNov 6, 2019
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
