Loading…
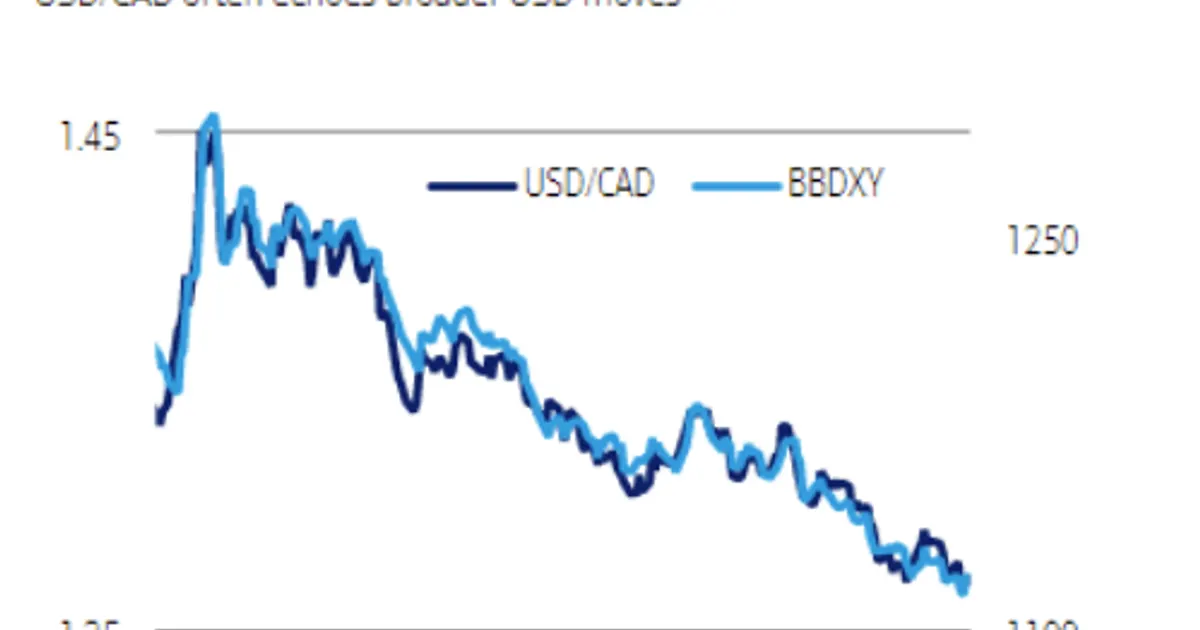
Bank of America research describes seasonal patterns in the Canadian dollar, which tends to appreciate moderately from April through June and depreciate in the fall. BofA links the pattern to broader USD seasonality, risk appetite and oil prices.
This is a seasonal outlook with no new cause, so it has little direct bearing on feed prices. It offers only a weak signal for the timing of Canadian-currency effects on imported ingredients.
 investinglive.comFeb 23, 2021
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
