Loading…
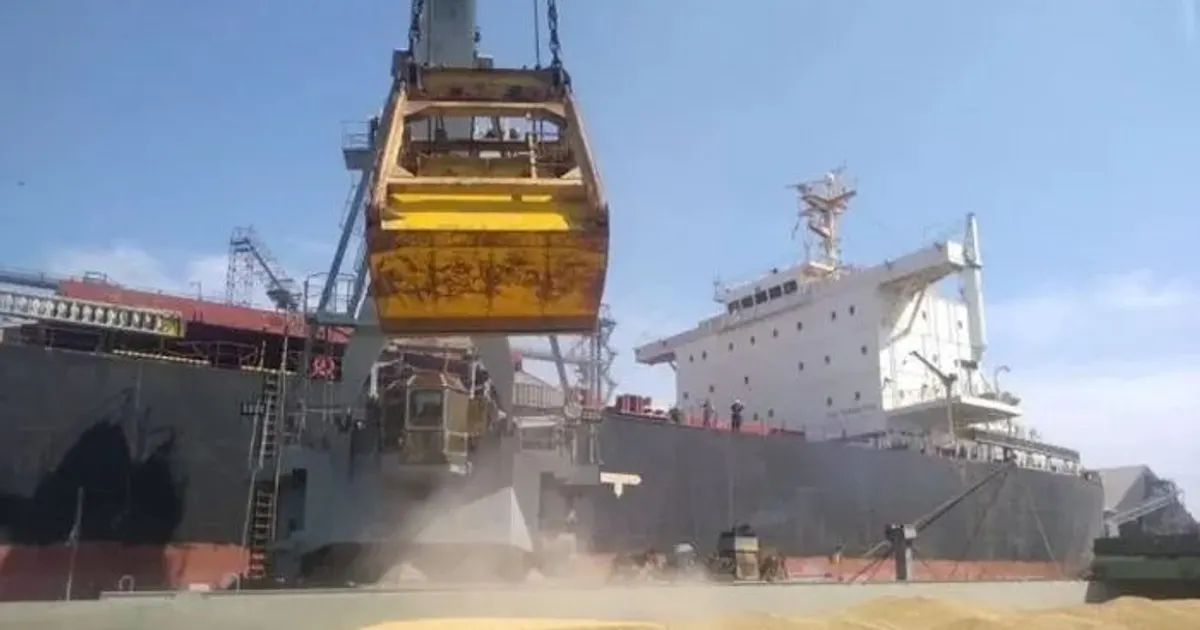
Russian grain exports via the Caspian Sea remain constrained by small river-sea vessels, shallow water and winter navigation limits that cut shipping by 60-70%. Freight rates are up about 25% year on year.
The route has a potential capacity of 10-13 million tonnes a year, but it does not serve Egypt or the Middle East, which previously took about 37% of Russian wheat purchases.
Limited Caspian capacity and higher freight mean Russian wheat cannot easily replace lost Black Sea volumes, keeping wheat export availability tight and freight costs elevated.
 ukragroconsult.comUkrAgroConsultOct 31, 2026
After 283 past bullish logistics events, Wheat (SRW) moved a median -0.2% over 5 sessions (46% higher; middle half -1.4% to +1.3%), and -0.1% over 20.
Not enough comparable past events yet for a historical read.
Moves of each commodity's benchmark from the last close before the event. Historical reads pool past events of the same kind; they describe what happened, not what will. Not investment advice.
