Yükleniyor…
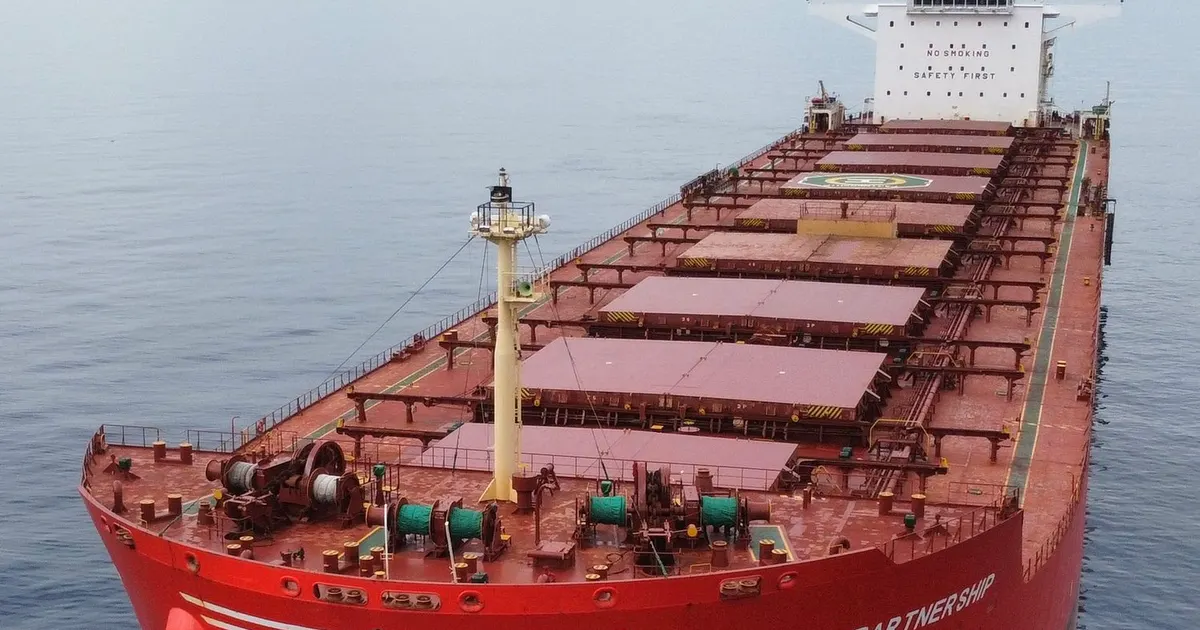
Dry bulk freight held relatively stable in late February, with Capesize Brazil to North China rates near the year's highs at just below $22 per tonne. Panamax Continent to Far East rates rose, while Supramax Indo rates stayed weak, and demand tonne-day growth continued to decline from late-2023 peaks.
Sustained strength on the Brazil-to-China capesize lane keeps ocean freight a cost component for Brazilian soy and feed exports to Asia, while slowing demand growth limits how much further rates can rise.
 breakwaveadvisors.comSignal Ocean21 Şub 2024
Tarihsel bir değerlendirme için henüz yeterli karşılaştırılabilir geçmiş olay yok.
230 geçmiş nötr lojistik olayları olayından sonra, Soya fasulyesi 5 seansta medyan +%0,4 hareket etti (%55 daha yüksek; orta yarı %-1,4 ile +%2,0 arası) ve 20 seansta +%0,1.
Her emtianın referansının olaydan önceki son kapanışa göre hareketi. Geçmiş okumalar aynı türdeki geçmiş olayları birleştirir; neyin olduğunu anlatır, neyin olacağını değil. Yatırım tavsiyesi değildir.
