読み込み中…
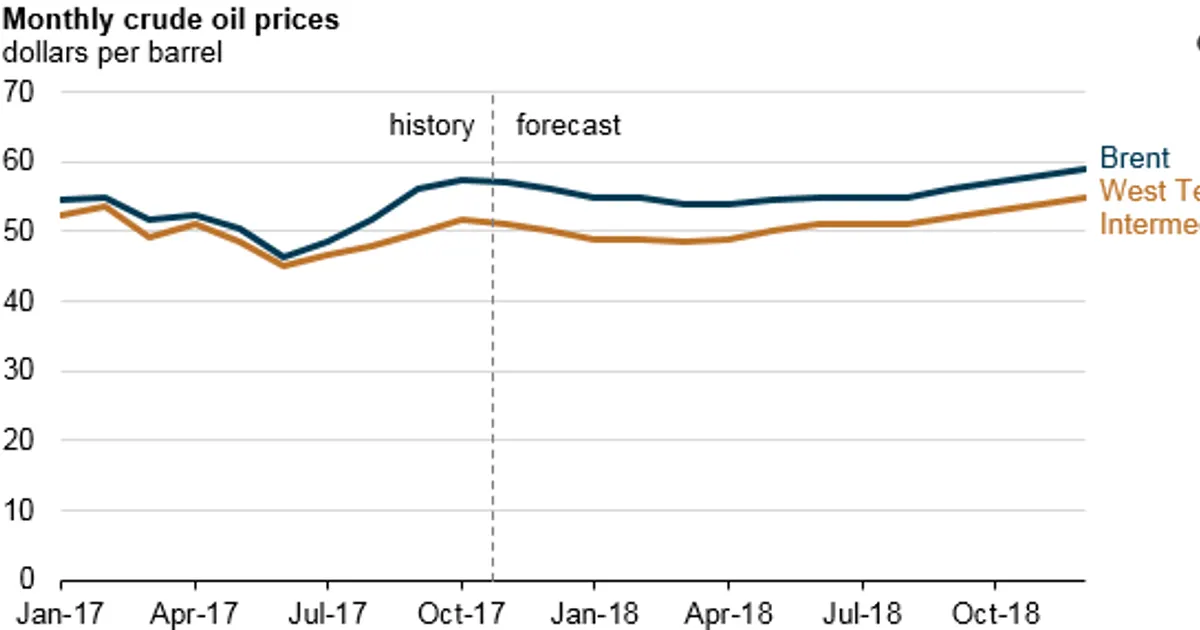
The EIA's November outlook forecasts the Brent-WTI spread at $6 per barrel through the first quarter of 2018, narrowing to $4 in the second half of 2018. The wider spread reflects transport bottlenecks moving crude from Cushing and the Permian basin to the U.S. Gulf Coast.
WTI averaged $6 below Brent in September and October.
Pipeline constraints keep inland U.S. crude discounted to Brent, which weighs on WTI-linked prices while Brent stays firmer. The effect on feed markets is indirect, through energy and biofuel input costs.
 eia.govU.S. Energy Information Administration (EIA) (.gov)2017/12/01
過去の弱気な物流イベント19件の後、原油(WTI) は5営業日で中央値 -1.5% 動き(37% が上昇。中央50%は -6.6% から +2.3%)、20営業日では +5.3% 動きました。
過去の強気な物流イベント22件の後、原油(ブレント) は5営業日で中央値 -0.7% 動き(45% が上昇。中央50%は -5.7% から +4.5%)、20営業日では -1.2% 動きました。
イベント直前の終値からの各商品ベンチマークの動き。過去の傾向は同種の過去イベントをまとめたものであり、起きたことを示すもので、今後を示すものではありません。投資助言ではありません。
