Caricamento…
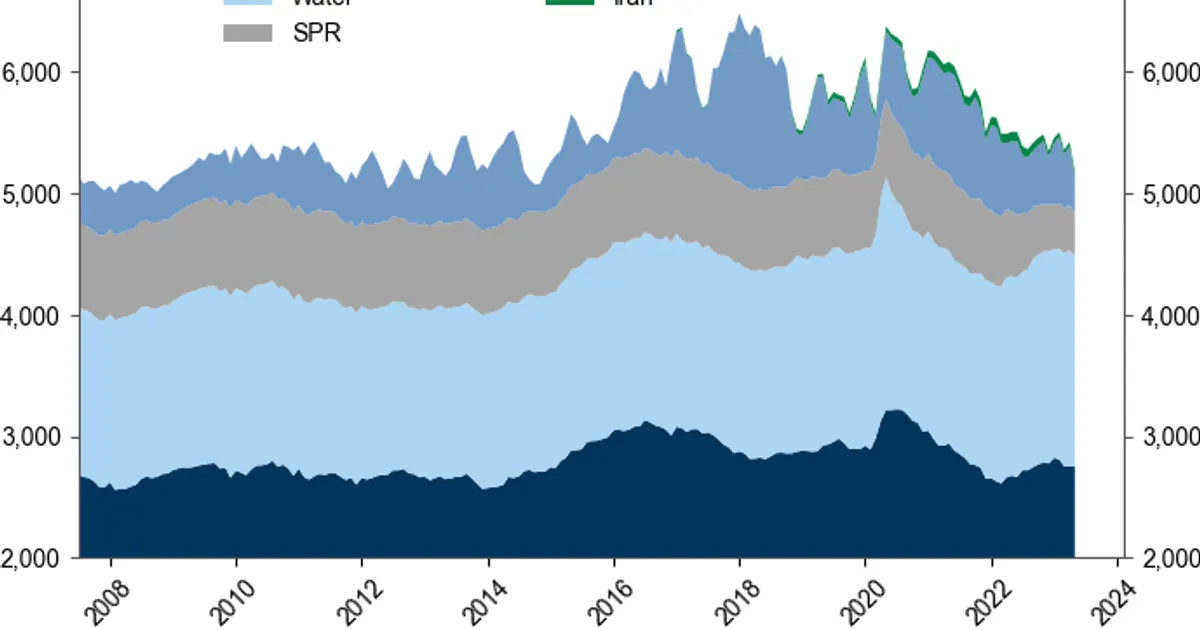
Goldman Sachs analysts argue that the sharp 2023 commodity sell-off reflects an unprecedented physical de-stocking rather than only financial liquidation. They cite large SPR drawdowns in France, China and the US totaling about 250 million barrels, falling Iranian floating storage, and weaker clean freight rates.
Their end-use demand and inventory data still look firm, but prices have moved against their bullish forecasts.
Government stock releases and sharply higher funding costs are draining physical inventories, which weighs on crude and energy-linked prices despite steady demand. For feed buyers, lower energy prices can ease costs for ethanol, biofuel and freight-linked inputs, but the price direction remains uncertain.
 gspublishing.com23 mag 2023
Dopo 565 eventi macro ribassista passati, Petrolio greggio (WTI) si è mosso in mediana di -1,4% in 5 sedute (41% in rialzo; metà centrale da -5,9% a +3,0%), e di -0,5% in 20.
Dopo 312 eventi macro ribassista passati, Petrolio greggio (Brent) si è mosso in mediana di -1,7% in 5 sedute (38% in rialzo; metà centrale da -5,4% a +2,3%), e di -1,7% in 20.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
