Caricamento…
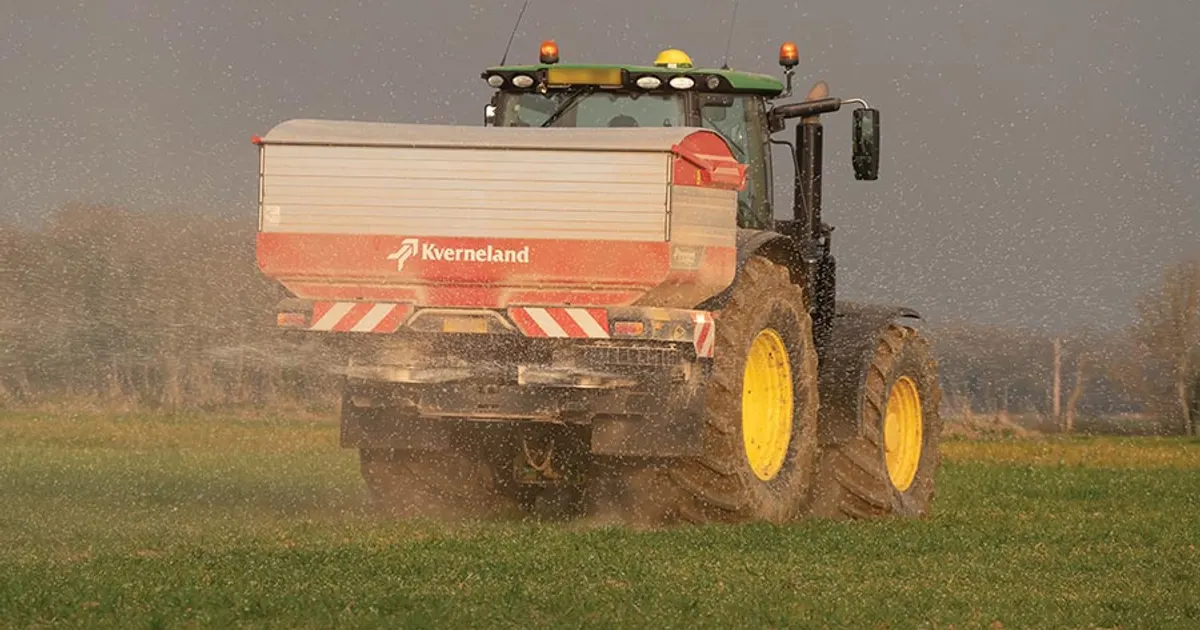
European ammonium nitrate plants are shutting down fully or partly due to high gas prices, with Polish plants Anwil and Grupa Azoty halting production and Lithuania's Achema due to close on 1 September. Imported AN was offered at £820-£835/t and urea rose to £745-£760/t delivered as buyers switched away from AN.
Gas-driven fertilizer supply cuts push nitrogen prices higher and the trade expects up to a 35% drop in fertilizer use for the coming crop, which could trim yields and raise grain costs.
 fwi.co.ukSuzie Horne23 ago 2022
Dopo 323 eventi geopolitica rialzista passati, Mais si è mosso in mediana di +0,5% in 5 sedute (57% in rialzo; metà centrale da -1,5% a +2,9%), e di +0,9% in 20.
Dopo 361 eventi geopolitica rialzista passati, Frumento (SRW) si è mosso in mediana di +0,7% in 5 sedute (58% in rialzo; metà centrale da -1,4% a +3,7%), e di +1,3% in 20.
Dopo 205 eventi geopolitica rialzista passati, Urea si è mosso in mediana di +0,4% in 5 sedute (53% in rialzo; metà centrale da -2,1% a +3,0%), e di -0,4% in 20.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
European gas-driven shutdowns of ammonium nitrate plants (Anwil, Grupa Azoty, Achema) tightened nitrogen fertiliser supply and pushed buyers to switch to urea, lifting delivered urea prices, though the report dates to 3 days before the move and the size of a 19% one-day jump suggests other drivers also contributed.
European AN plant shutdowns pushed buyers toward urea, raising urea demand and delivered prices (£745-760/t).
