Caricamento…
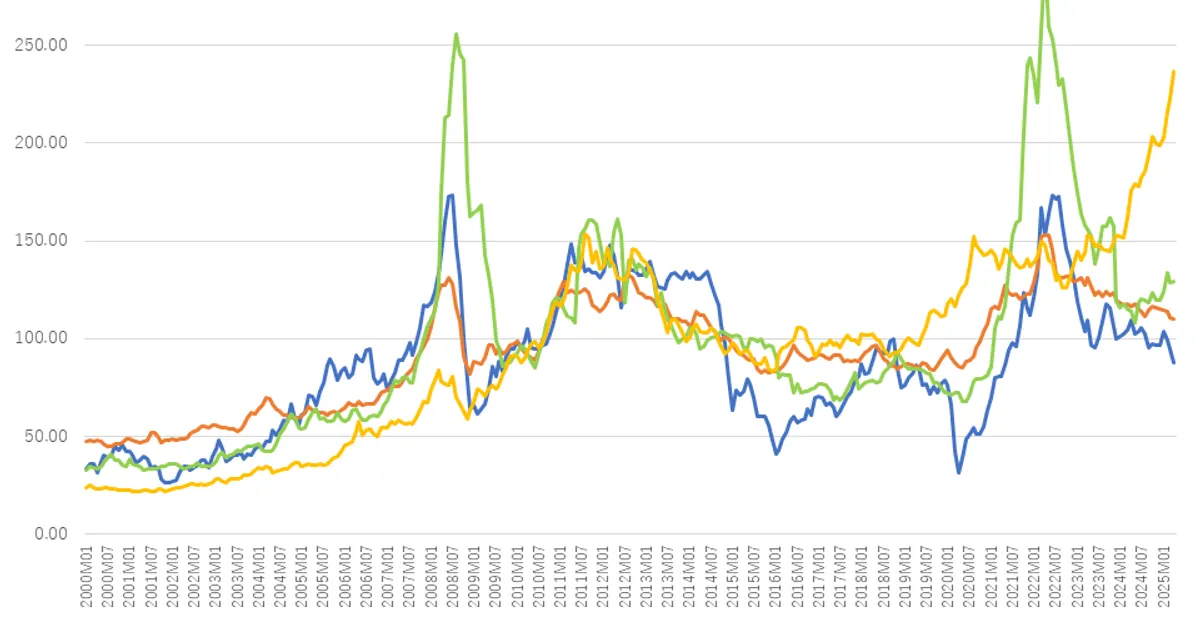
JIRCAS republished an AMIS overview of recent fertilizer market trends, noting about 169 million tonnes expected to be traded in 2024. It describes China's export restrictions since 2021, which cut its urea and phosphate exports by 95% and 21% since 2020, and the effects of sanctions on Belarus and the Ukraine conflict on regional supply.
Persistent export curbs from China and Russian/Belarusian supply constraints keep fertilizer costs elevated, which raises input costs for feed-grain producers and supports the case for higher corn and soy production costs.
 jircas.go.jpJapan International Research Center13 mag 2025
Dopo 92 eventi macro rialzista passati, Urea si è mosso in mediana di +0,0% in 5 sedute (50% in rialzo; metà centrale da -2,0% a +3,6%), e di +4,8% in 20.
Dopo 28 eventi macro rialzista passati, DAP si è mosso in mediana di -0,2% in 5 sedute (36% in rialzo; metà centrale da -0,9% a +1,3%), e di -0,8% in 20.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
