Caricamento…
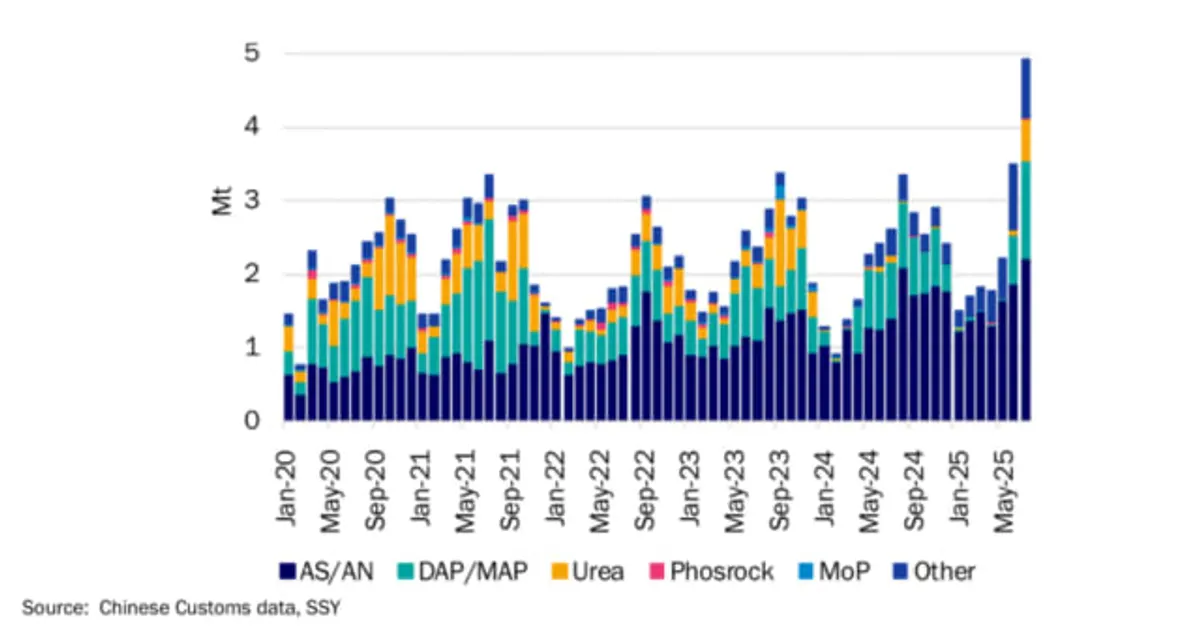
Fertiliser prices have reached multi-year highs, with China halting exports to India and Chinese fertiliser shipments in July hitting decade-high levels. US NOLA urea peaked at $455/st in May before easing to $400/st in September, and DAP and potash prices were sharply higher year-on-year.
Chinese DAP/MAP exports restarted in June, with July volumes at a three-year high of 1.3 Mt.
Chinese export policy and Middle East gas outages are the key swing factors for nitrogen and phosphate prices. Higher fertilizer costs raise the production cost of feed grains and oilseeds, and cumulative Chinese phosphate exports remain well below last year.
 ssyglobal.comSSY23 set 2025
Dopo 23 eventi commercio neutrale passati, Urea si è mosso in mediana di 0,0% in 5 sedute (48% in rialzo; metà centrale da -1,1% a +1,0%), e di +2,8% in 20.
Dopo 193 eventi commercio rialzista passati, DAP si è mosso in mediana di +0,4% in 5 sedute (54% in rialzo; metà centrale da -0,3% a +1,8%), e di +1,9% in 20.
Ancora troppi pochi eventi passati comparabili per una lettura storica.
Variazioni del benchmark di ciascuna materia prima rispetto all'ultima chiusura prima dell'evento. Le letture storiche raggruppano eventi passati dello stesso tipo; descrivono ciò che è accaduto, non ciò che accadrà. Non è consulenza di investimento.
