Cargando…
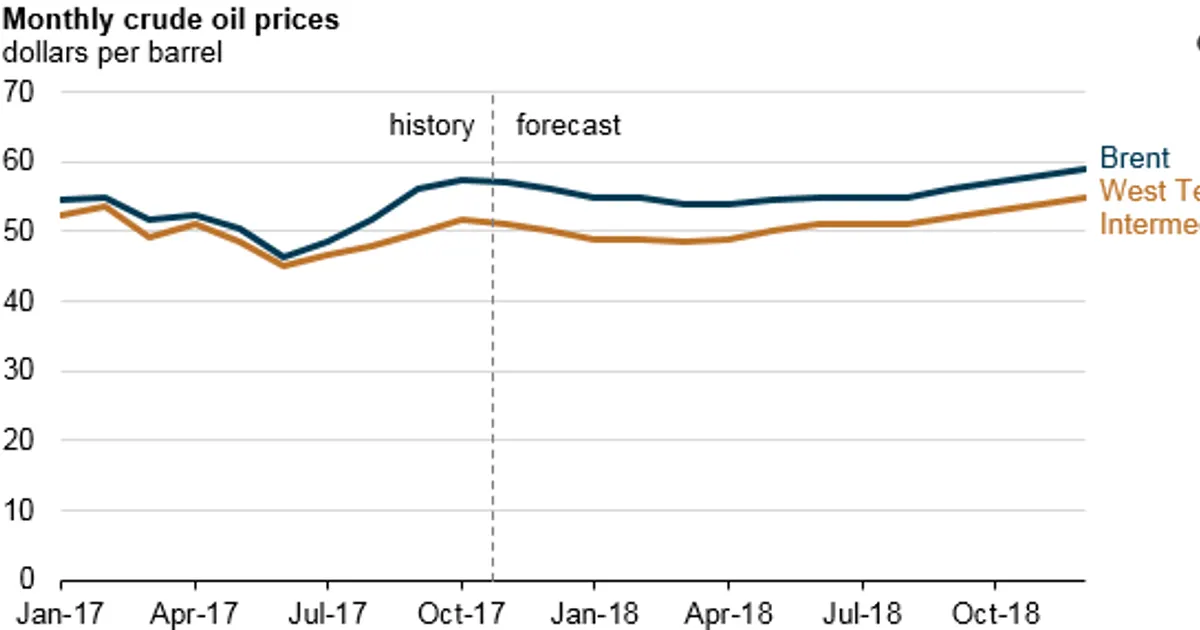
The EIA's November outlook forecasts the Brent-WTI spread at $6 per barrel through the first quarter of 2018, narrowing to $4 in the second half of 2018. The wider spread reflects transport bottlenecks moving crude from Cushing and the Permian basin to the U.S. Gulf Coast.
WTI averaged $6 below Brent in September and October.
Pipeline constraints keep inland U.S. crude discounted to Brent, which weighs on WTI-linked prices while Brent stays firmer. The effect on feed markets is indirect, through energy and biofuel input costs.
 eia.govU.S. Energy Information Administration (EIA) (.gov)1 dic 2017
Tras 19 eventos bajista de logística pasados, Petróleo crudo (WTI) se movió una mediana de -1,5 % en 5 sesiones (37% al alza; mitad central entre -6,6 % y +2,3 %), y +5,3 % en 20.
Tras 22 eventos alcista de logística pasados, Petróleo crudo (Brent) se movió una mediana de -0,7 % en 5 sesiones (45% al alza; mitad central entre -5,7 % y +4,5 %), y -1,2 % en 20.
Variaciones de la referencia de cada materia prima desde el último cierre antes del evento. Las lecturas históricas agrupan eventos pasados del mismo tipo; describen lo ocurrido, no lo que ocurrirá. No es asesoramiento de inversión.
