Cargando…
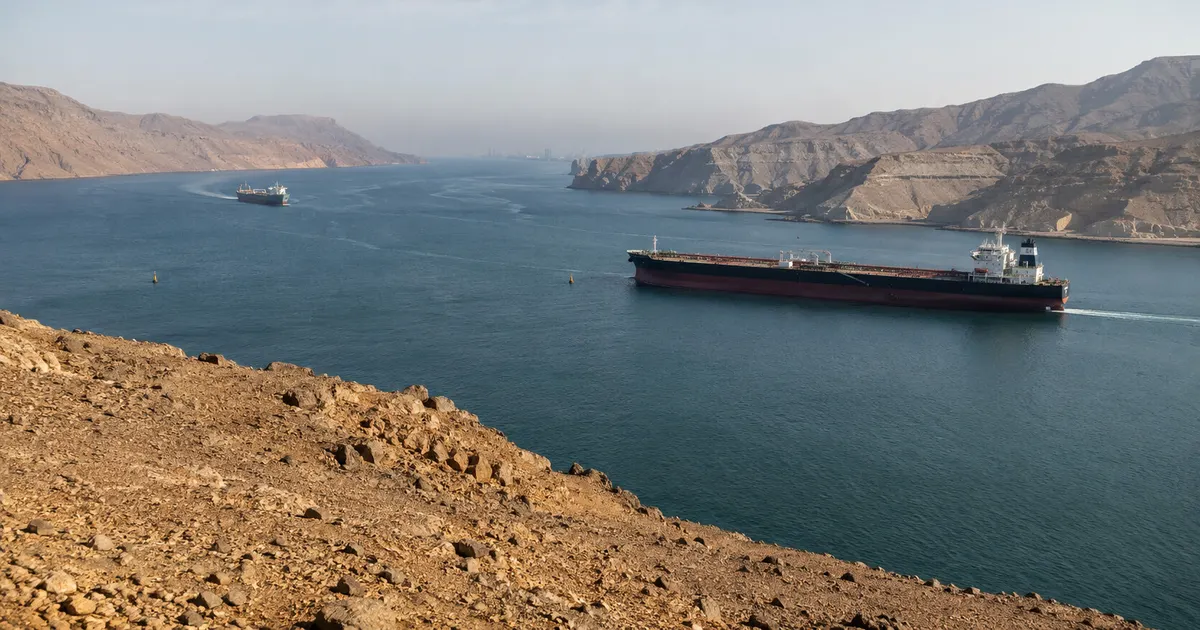
The WTO-AXSMarine tracker shows fertilizer shipments through the Strait of Hormuz staying near zero in early September 2026. Middle Eastern producers are rerouting cargoes via the Red Sea, Suez and pipelines at higher cost.
Iran and Oman agreed on safe shipping coordinates in August, but insurance and security concerns have kept traffic from recovering. Sulfur prices remain above $1,000/t, and phosphate output is being cut in Egypt, Brazil and India.
With roughly 20% of global nitrogen trade normally passing through Hormuz, the blockage keeps urea supply tight and raises freight costs. Reduced phosphate output from sulfur shortages supports DAP prices.
 ukragroconsult.com14 sept 2026
Tras 49 eventos alcista de logística pasados, Urea se movió una mediana de -0,3 % en 5 sesiones (45% al alza; mitad central entre -1,3 % y +2,2 %), y -0,4 % en 20.
Tras 31 eventos alcista de logística pasados, DAP se movió una mediana de +0,5 % en 5 sesiones (58% al alza; mitad central entre -0,4 % y +0,9 %), y +1,6 % en 20.
Variaciones de la referencia de cada materia prima desde el último cierre antes del evento. Las lecturas históricas agrupan eventos pasados del mismo tipo; describen lo ocurrido, no lo que ocurrirá. No es asesoramiento de inversión.
