Cargando…
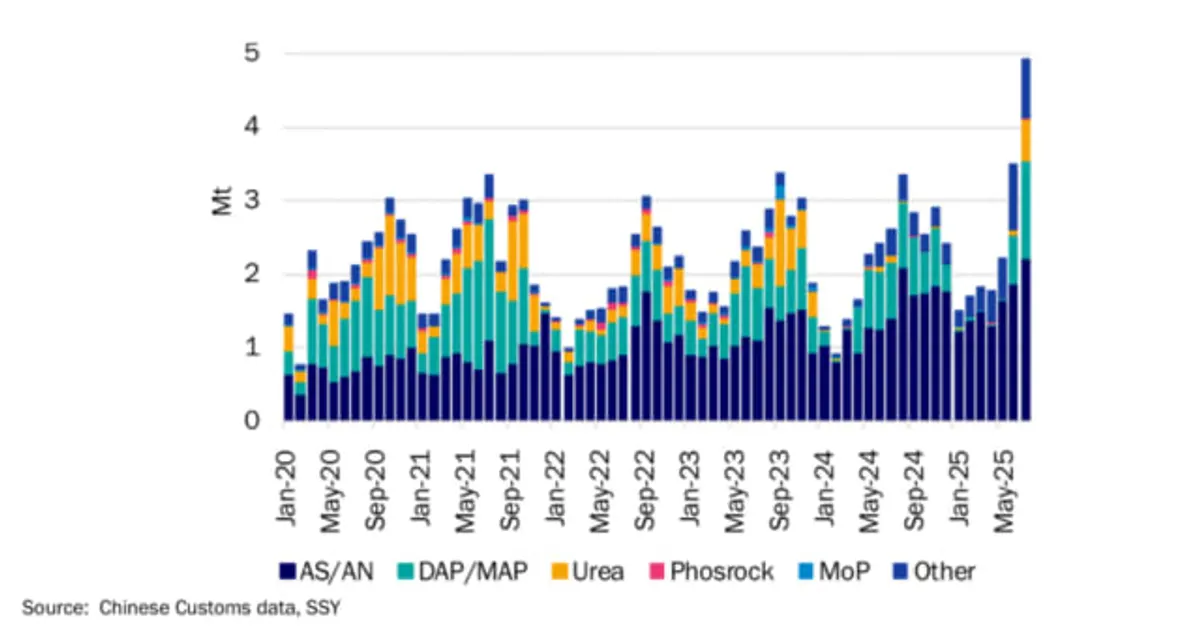
Fertiliser prices have reached multi-year highs, with China halting exports to India and Chinese fertiliser shipments in July hitting decade-high levels. US NOLA urea peaked at $455/st in May before easing to $400/st in September, and DAP and potash prices were sharply higher year-on-year.
Chinese DAP/MAP exports restarted in June, with July volumes at a three-year high of 1.3 Mt.
Chinese export policy and Middle East gas outages are the key swing factors for nitrogen and phosphate prices. Higher fertilizer costs raise the production cost of feed grains and oilseeds, and cumulative Chinese phosphate exports remain well below last year.
 ssyglobal.comSSY23 sept 2025
Tras 23 eventos neutral de comercio pasados, Urea se movió una mediana de 0,0 % en 5 sesiones (48% al alza; mitad central entre -1,1 % y +1,0 %), y +2,8 % en 20.
Tras 193 eventos alcista de comercio pasados, DAP se movió una mediana de +0,4 % en 5 sesiones (54% al alza; mitad central entre -0,3 % y +1,8 %), y +1,9 % en 20.
Todavía no hay suficientes eventos comparables pasados para una lectura histórica.
Variaciones de la referencia de cada materia prima desde el último cierre antes del evento. Las lecturas históricas agrupan eventos pasados del mismo tipo; describen lo ocurrido, no lo que ocurrirá. No es asesoramiento de inversión.
