Lädt…
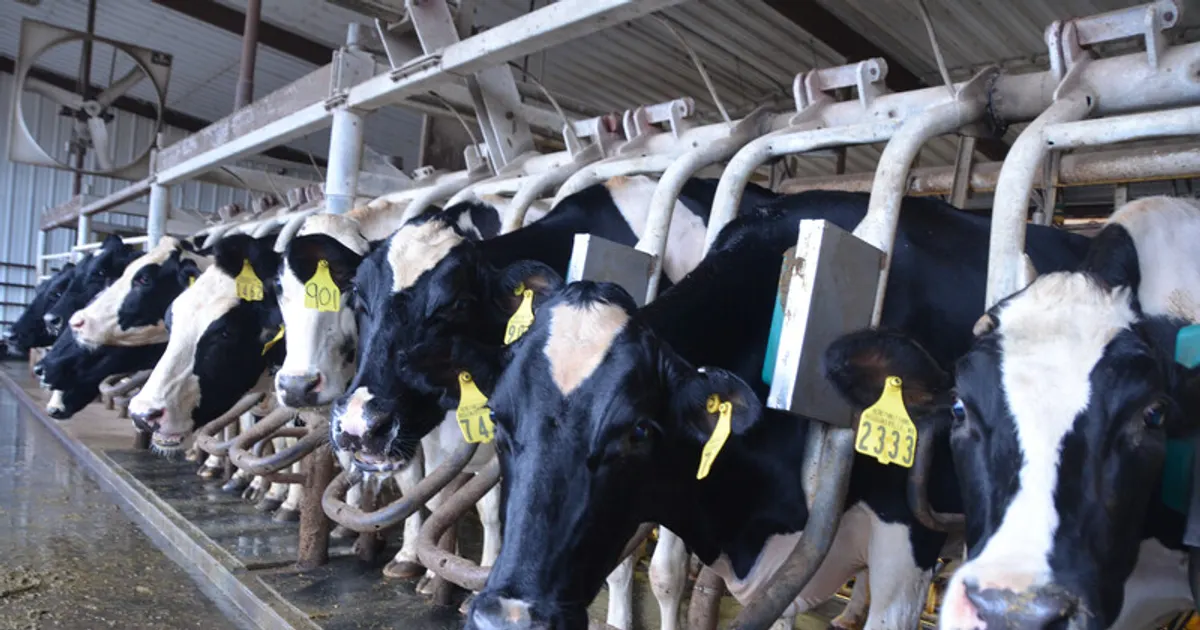
A University of Wisconsin outlook reports that US milk production grew less than 1% from late 2018 into 2019, with March output down 0.6% year on year. Dairy product output and stocks have tightened, with butter, cheese and nonfat dry milk production down, and prices are expected to keep strengthening through the year.
Tighter milk supply and firming dairy product prices point to higher Class III and Class IV milk prices, which support dairy herd economics and the value of dairy-related feed demand.
 en.edairynews.comDamián Morais31.05.2019
Nach 237 vergangenen Ereignisse (bullisch, Bericht) bewegte sich Milch (Class III) im Median über 5 Handelstage um +0,0 % (51% höher; mittlere Hälfte -0,3 % bis +0,6 %) und über 20 Handelstage um +1,2 %.
Veränderungen des Benchmarks jedes Rohstoffs seit dem letzten Schluss vor dem Ereignis. Historische Werte bündeln frühere Ereignisse derselben Art; sie beschreiben, was passiert ist, nicht was passieren wird. Keine Anlageberatung.
